Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
Learn if this source of short-term financing can help your business.
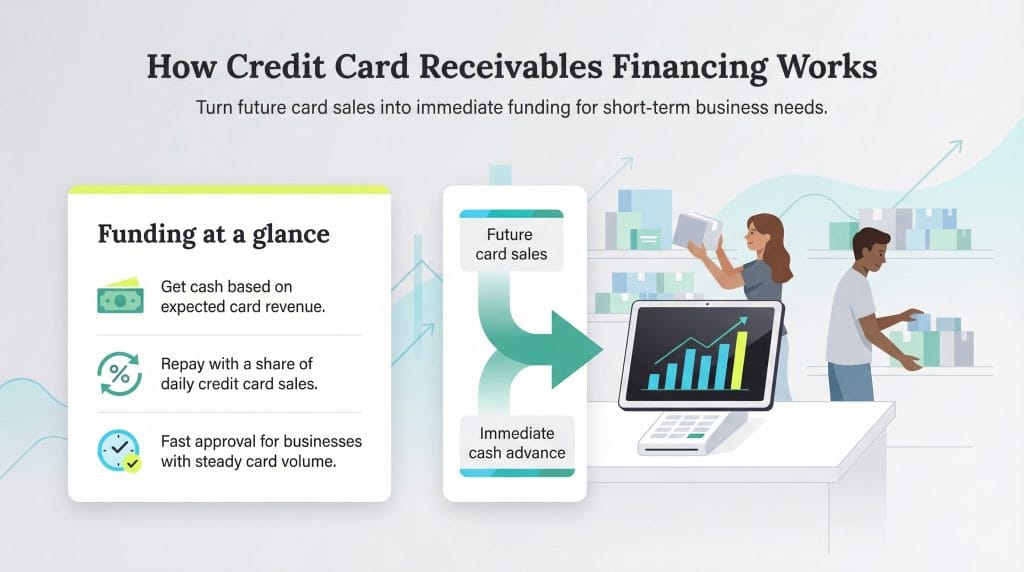
Businesses that accept credit card payments often have a solid grasp on their short-term revenue projections. Yet, unexpected expenses or delays may lead to a pressing cash crunch, making it difficult to wait for credit card transactions to clear. Credit card receivables financing offers businesses a way to access that money immediately.
We’ll explain more about credit card receivables financing, its key features and the potential benefits for small business owners.
Credit card receivables financing, also known as credit card factoring or merchant cash advances (MCA), is a viable source of short-term financing for small businesses that can’t get traditional bank loans.
Unlike traditional lenders, credit card receivables financing companies ― which may include your current credit card payment processor ― consider your business’s future credit card sales a business asset, so they advance capital based on your projected credit card sales.
Tornike Asatiani, CEO of Edumentors, noted that growing businesses often encounter payment delays that can slow operations.
“Credit card receivables financing helps by turning future sales into immediate funds,” Asatiani explained. “Instead of fixed monthly payments, a percentage of daily sales goes toward repayment.”
The best credit card processors have reasonable fees, a straightforward payment process and exceptional customer service. Many will be willing to work with you on credit card factoring.
Credit card receivables financing services provide cash advances that small business owners can use to:
These companies advance funds based on your future credit card sales and repayment is made through a predetermined percentage deducted from daily credit card revenue. You can pay the credit card receivables company directly or it may direct its payment processor to take payments.
For example, let’s say a new retail store must purchase a large inventory stock to prepare for the holiday shopping season. While it has ongoing credit card revenue, it doesn’t have enough in the bank to purchase the $20,000 worth of inventory it needs.
A credit card receivables company advances the retailer $20,000, charging a fee between $2,000 and $10,000. The retailer uses the funds to buy inventory. Each month, 15 percent of the store’s credit card revenue is deducted until the total $20,000 plus fees are repaid.
Credit card receivables financing providers consider a business’s credit card sales to determine its monthly credit card revenue. They also look at the business owner’s credit score and a few other factors, including:
Credit card receivables companies use this information to determine the amount of capital it’s willing to advance, the fee and the repayment percentage. Most businesses with steady credit card sales can get approved. Typically, the approval and funding process is completed within two weeks.
According to Federal Reserve data, 82 percent of MCA applications were partially or fully approved, reflecting a high approval rate compared to other financing options.
This form of financing is a good option in the following circumstances:
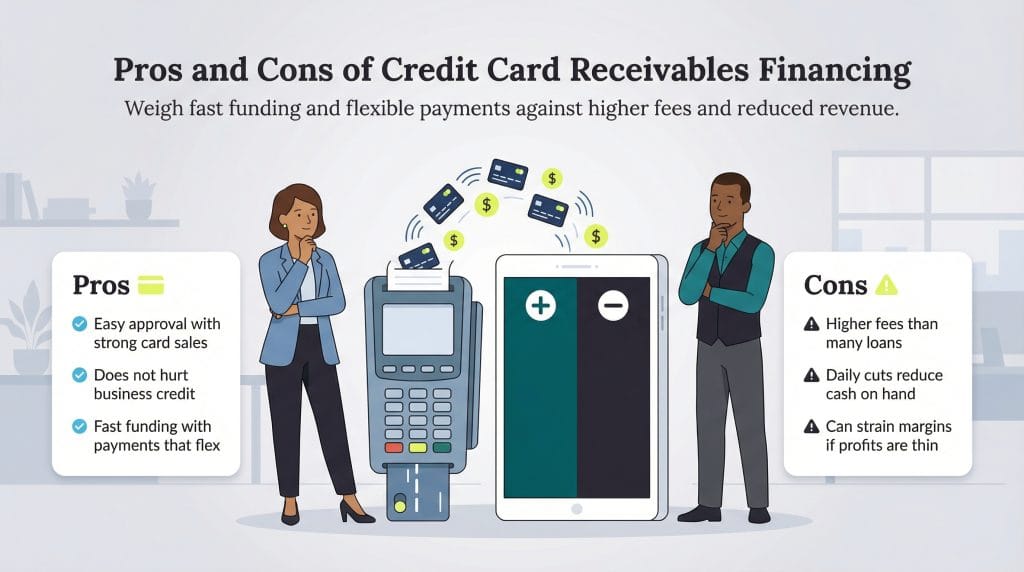
Von Aulock advised businesses to carefully evaluate whether credit card receivables financing is the right move for them.
“The costs are typically higher than traditional financing and it can put a real strain on your cash flow if you’re not careful,” Von Aulock cautioned. “But when used strategically — with clear eyes on the true costs and a solid plan for using the capital — it can be a powerful tool for growth.”
If credit card receivables financing isn’t for you, you have various other financing options, including:
If you’d like to pursue a loan, check out our reviews of the best business loans and financing options. We outlay criteria to help you choose the best business loan for your company.
The repayment term for credit card receivables financing is typically between 30 days and six months but can extend to several years.
Credit card receivables financing amounts usually range from $3,000 to $300,000, depending on the business’s needs, revenue and other qualifications.
Most businesses get their credit card receivables financing cash within one or two days, but it can sometimes take as long as two weeks.
Since the loan is secured with future credit card sales, your credit score is less important with credit card receivables financing than other financing types. Business owners with credit scores as low as 500 have gotten approved. However, your credit score will impact the amount you can borrow and the fee you pay.
If you have little or no balance on your business credit card and a relatively low interest rate, it might be better to use your credit card because repayment is more flexible. Using your business credit card can benefit you if you have one that gives you rewards like cashback or travel credits.
However, if you need more than your card’s available credit limit or your card has a very high interest rate, you should look into credit card receivables financing.
The overall fee for credit card receivables financing is based on a factor rate, usually between 1.1 and 1.5. This means you’ll repay anywhere from 110 percent of the loan amount (equivalent to a 10 percent interest rate if your term is 12 months) to 150 percent (a very hefty 50 percent interest rate for a one-year term).
The factor rate depends on your business’s qualifications, including your credit history, length of time in business, monthly credit card volume and other factors.
The MCA provider deducts a percentage of your daily or weekly credit card sales revenue, called the holdback rate. The usual holdback rate ranges between 10 percent and 20 percent of credit card volume. Once the money deducted via the holdback rate equals the fee calculated by the factor rate, your loan is paid off.
Additional fees may also apply, such as an origination fee, an underwriting fee (also called a funding fee) and an administrative fee. Read your agreement carefully before signing it to ensure you understand all the costs and terms.