Your free business.com+ membership unlocks exclusive tech deals and advisor support
Join Free
BDC Hamburger Icon

Menu

Close
BDC Logo with Name
Search Icon
Search Icon
Advertising Disclosure
Close
Advertising Disclosure

Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.

As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.

Should You Go Global?

Is international expansion a good fit for your company? See the pros and cons, and what questions to ask yourself before expanding globally.

Mark Fairlie
Written by:
Mark Fairlie, Senior Analyst
author image
Editor verified:
Gretchen Grunburg,Senior Editor
Last Updated Oct 22, 2026
Business.com earns commissions from some listed providers. Editorial Guidelines.
Table Of Contents Icon

Table of Contents

Open row

Technology, international trade and a more interconnected world have made it easier than ever for businesses to expand beyond their home countries. But entering a new market comes with challenges, and opening new locations overseas isn’t the right move for every company. We’ll explore the benefits and drawbacks of international expansion, the questions to ask before taking the leap and how to get started if you decide to go global.
Benefits of global expansion

benefits of global expansion

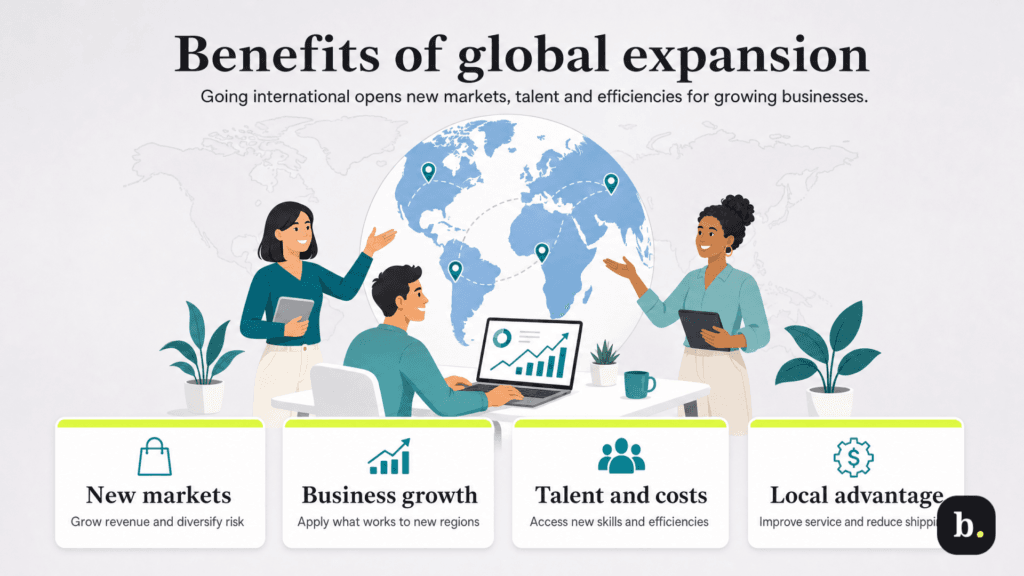
Expanding internationally can open up new opportunities for businesses that are ready to grow beyond their home markets. Here are some potential benefits of going global:

  • Access to new markets: Entering international markets can help you reach new customers, generate additional revenue and reduce your dependence on your domestic market. According to McKinsey research analyzing 5,000 of the world’s largest companies, businesses that expanded internationally generated 1.9 percentage points more annual total shareholder returns than their industry peers.
  • Business growth opportunities: If growth opportunities are limited at home, expanding internationally gives you a chance to build on what’s already worked for your business. You can apply your experience and expertise in a new market, adapting your products, services and marketing to local customers.
  • Access to new labor markets: Expanding overseas gives you access to a wider talent pool, which can be particularly helpful if you’re struggling to recruit new employees with specialized skills. Establishing a local presence may also simplify the hiring process. Depending on your industry, moving some production overseas could also reduce labor or manufacturing costs.
  • Lower shipping costs: Retailers and wholesalers that establish overseas distribution or production facilities may be able to reduce shipping distances and transportation costs. This can help them offer more competitive prices to customers in those markets.
  • Better customer service: Having employees or support teams in another country can make it easier to serve customers in their own language and time zone. Local teams can also help you build stronger relationships and provide excellent customer service to clients abroad.
  • Increased cost efficiency: International expansion may help you achieve economies of scale as your business grows. Access to new suppliers, production facilities and other resources could also help lower your operating costs.
  • Financial incentives: Some countries offer tax breaks, grants and other incentives to attract foreign businesses. Depending on where you expand, these programs could help offset some of the costs of establishing operations in a new market.

Downsides of international market expansion

Expanding into international markets can be a great way to grow your business, but there are some drawbacks to consider. Here are a few potential challenges you should be aware of:

  • High startup costs: Launching a business in a new country can be expensive. Along with setting up facilities or offices, you may face substantial costs for legal services, hiring, marketing and infrastructure. It could also take months or years before your overseas operations generate enough revenue to cover those expenses.
  • Costly exit expenses: If your international expansion doesn’t go as planned, pulling out of a market can be expensive, too. You may face penalties for breaking leases, terminating employees and ending supplier agreements.
  • Reliance on local expertise: You may need to hire local contractors, consultants and other professionals to navigate legal requirements and HR compliance challenges. You’ll also need to figure out how to process payroll, establish local sales processes and recruit employees. An international PEO can help with many of the employment-related tasks, but these services add to your costs.
  • Exchange-rate fluctuations: Changes in exchange rates can eat into your profits. For example, if the local currency loses value against the U.S. dollar, the money you earn overseas will be worth less when you convert it to dollars. You could also end up paying more for imported supplies and materials.
  • Complex performance oversight: Even if you’re tracking key performance indicators (KPIs), managing operations from thousands of miles away can be challenging. Differences in time zones, business practices and workplace cultures can make it harder to spot problems and respond quickly. These are common challenges of geodiversity.
  • Language and cultural barriers: Winning customers in another country requires an understanding of local languages, customs and expectations. You’ll need to adapt your marketing, communications and customer service to the new market. What works with customers at home may not have the same appeal overseas.
  • Compliance and regulatory issues: Every country has its own laws and regulations, and failing to comply can result in substantial penalties. In fact, in a 2026 HSBC survey, 34 percent of businesses cited regulatory and trade policy issues as one of their top three barriers to international expansion. You’ll need to research local employment laws, tax obligations, trade restrictions and industry-specific requirements. For example, a pharmaceutical manufacturer may need regulatory approval before selling its products in a new market. (We’ll dive deeper into regulatory considerations below.)
  • Changing tariffs and trade policies: A change in tariffs can make imported materials more expensive or push up the price of products you sell overseas. Trade restrictions can also affect which countries you can buy from or sell to. And with trade policies subject to change, it can be difficult to predict your costs or set prices with confidence. Keep an eye on developments in your target markets and consider how your business would handle an unexpected increase in costs.
FYIDid you know

Finding business investors may help you cover some of the costs of international expansion. However, bringing in outside investors can mean giving up some ownership or control of your business, so weigh your financing options carefully.
Questions to ask yourself before expanding internationally

questions to ask before globally expansion
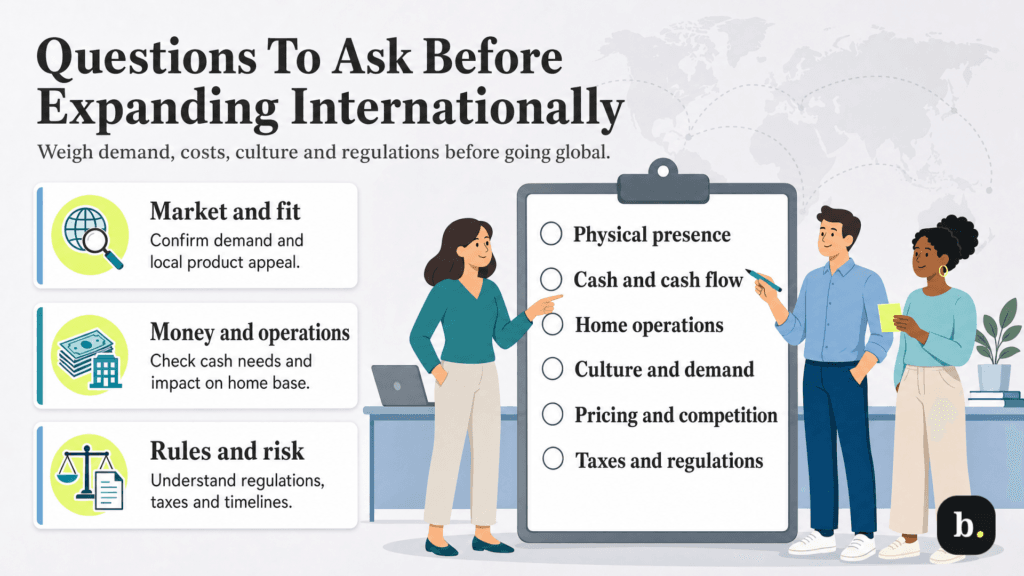
Ask yourself the following questions before expanding internationally.

Global expansion can be a big undertaking, and you’ll want to make sure your business is ready for it. Before you and your C-suite team commit to expanding internationally, consider the following questions:

Do you really need a physical presence overseas?

Are you sure you can’t serve international customers from your current location? You don’t have to go all out to go global, especially at first.

You might start by selling products to international customers through your website or an online marketplace, or work with a local distributor who already knows the market. Licensing your products or franchising your business may also be options, depending on what you sell. The Uppsala model of international expansion describes how companies often expand gradually, building experience in foreign markets before making larger investments.

Do you have the cash to go global?

International expansion has a way of costing more and taking longer than planned. And the last thing you want is to run short of money just as your overseas business starts gaining traction. Take a hard look at your cash flow and make sure you have enough cash to cover the initial investment and weather a slow start.

Can you afford to neglect your home operation?

Getting a business up and running overseas can demand a lot of your attention, sometimes at the expense of your operations back home. You or other senior managers may need to spend weeks or even months at the new location, leaving your home team to handle things without you. Are you confident they can keep everything running smoothly while you’re away?

Have you considered the cultural factors involved in international expansion?

Doing business in another country means getting used to different customs, expectations and ways of communicating. For example, business relationships in some countries depend heavily on personal connections, while in others, people prefer to get straight down to business. You’ll also need to understand local attitudes toward negotiations, decision-making and religious traditions. Take the time to learn about the culture of your target market before you expand. A misunderstanding that seems minor to you could cost you a valuable business relationship.

Will your product sell in an international market?

Your product or service might be in constant demand at home, but that doesn’t mean customers overseas will be lining up to buy it. Before investing in a new market, conduct focus groups, analyze potential customer segments and gather customer feedback to see whether there’s enough demand to make expansion worthwhile.

When choosing where to expand, consider countries that have something in common with your home market. Canada, for example, may be a good starting point for U.S. businesses because it’s close by and shares many cultural similarities, although recent tariff disputes have complicated trade between the two countries. Emerging markets are worth considering, too. India offers opportunities, but you’ll need to be prepared for different regulations, customer preferences and ways of doing business.

Of course, a promising economy doesn’t necessarily mean a promising market for your particular product. The Department of Commerce’s International Trade Administration publishes Country Commercial Guides with information on market conditions, trade barriers and business practices in more than 70 markets. They’re a good place to start your research.

Can you price competitively and still make good money?

Before entering a new market, find out what local competitors charge and whether you can match their prices while still turning a decent profit. Factor in shipping costs, tariffs, taxes and other expenses that could eat into your margins. And remember that trade policies can change, potentially making your products more or less competitive. If you can’t beat established competitors on price, what can you offer that they don’t? Better quality, specialized products or exceptional customer service might give customers a reason to pay more.

Are well-known brands already in your target country?

Breaking into a new market can be tough when customers already know and trust the competition. Research the biggest players in your target country, how much of the market they control and what makes customers loyal to them. Think about how much time and money it will take to make your brand known. If established competitors already dominate the market, you may face an uphill battle.

TipBottom line

Your brand should still be recognizable when you expand overseas, but your marketing campaigns may need some adjustments to appeal to local customers. If you plan to work with social media influencers, do your homework before signing anyone on. Make sure their audience and reputation are a good fit for your business.

Are you prepared to work under different regulatory regimes?

Every country has its own rules for doing business, and you’ll need to know which ones apply to you. If you’re exporting goods from the U.S., for example, check the Department of Commerce’s Bureau of Industry and Security to see whether your products are subject to export controls. You’ll also need to look into local employment laws, licensing requirements, data protection rules and taxes (more on those below).

The European Union presents an interesting situation because its member countries share many regulations, but individual countries have their own requirements, too. Depending on what you sell, you may need special approvals, certifications or licenses. You might also have to translate product labels, packaging and advertising materials into local languages.

Are you clear on how to maximize tax efficiency and compliance?

Taxes can get complicated when you’re doing business in more than one country. You’ll need to understand the tax laws in your target market, as well as any tax treaties with the U.S. that could affect what you owe. An international tax adviser can help you structure your overseas operations to avoid unnecessary taxes while staying compliant.

Banking can present challenges, too. Some foreign banks are reluctant to work with U.S.-owned businesses because of the reporting requirements under the Foreign Account Tax Compliance Act. And even if you find a bank willing to work with you, opening an account could take months because of identity verification and other compliance requirements. Be sure to factor that time into your expansion plans.

How to expand business globally

Image not found.
Establishing your overseas infrastructure is the first step in going global.

Once you’ve weighed the pros and cons, done your homework on potential markets and decided international expansion makes sense for your business, it’s time to figure out how to make it happen. Here are some steps to help you get started.

1. Establish your overseas operations.

Getting your overseas operations up and running takes some planning, particularly when it comes to staffing and communication. Here are a few things to take care of before and after your launch:

  • Get communication systems in place: Your home and overseas teams need reliable ways to stay in touch, share information and work together. Set up video conferencing, messaging and other communication tools and establish expectations for meetings and updates. Remember that time zone differences can make even a simple phone call tricky.
  • Familiarize yourself with local resources and customs: Learn about local business practices and customs before you launch, and lean on your local employees for guidance once you’re established. Follow international business etiquette and make sure your policies and procedures account for differences in language, employment practices and regulations.
  • Cultivate local talent: You may need to rely on managers from your home office in the beginning, but that can get expensive and stretch your leadership team thin. Recruit local employees who know the market, and look for promising candidates who can eventually take on management responsibilities.
  • Train managers who will be transferred overseas: Managers who do well at home won’t necessarily know how to lead a team in another country. Prepare them for differences in workplace expectations, communication styles and local customs. Investing in employee training before they relocate can make the transition easier for everyone.
  • Consider local partnerships to mitigate risks: Working with an established local business can help you cut business expenses and avoid having to build everything from scratch. Depending on your business, you might work with a distributor, form a joint venture or establish a franchise. Choose your partners carefully, though. A bad partnership can create more problems than it solves.
FYIDid you know

Want to hire employees overseas without setting up a local company? An employer of record (EOR) can handle employment contracts, payroll, benefits and local employment requirements on your behalf. Unlike a traditional professional employer organization (PEO), an EOR generally allows you to hire in countries where you don’t have your own legal entity.

2. Take advantage of government assistance.

You don’t have to figure out international expansion entirely on your own. The Small Business Administration (SBA) has several programs to help small businesses start selling overseas or expand their existing export operations, including the following:

  • Export loan programs: If you need money to get started, the SBA offers three main export loan programs: Export Express, with loans up to $500,000; Export Working Capital, with loans up to $5 million to help fulfill export orders; and International Trade loans, with up to $5 million for eligible equipment, facilities and working capital needs. You can find details on the SBA’s export financing page.
  • State Trade Expansion Program (STEP): Through STEP, the SBA provides funding to states and territories to help small businesses find customers overseas. Depending on where you’re located, you may be able to get assistance with trade shows, international marketing, translation services and other export-related expenses.
  • Export training and guidance: The SBA also offers resources to help businesses research foreign markets, prepare for exporting and understand their financing options. Its export and trade assistance program can connect you with specialists who work with small businesses entering international markets.

The SBA isn’t your only option for help with international expansion. Other federal agencies offer guidance, financing and resources to help U.S. businesses enter foreign markets, including the following:

  • U.S. Commercial Service: Part of the Department of Commerce’s International Trade Administration, the U.S. Commercial Service helps businesses identify promising overseas markets, find potential customers and partners and understand local business requirements. Its export counselors can be particularly helpful if you’re new to international sales.
  • Export-Import Bank of the United States (EXIM): The EXIM Bank helps U.S. exporters manage financial risks and secure financing. Its programs include export credit insurance to protect against foreign buyers who don’t pay, as well as loan guarantees that can help businesses obtain working capital. Some insurance policies also cover losses from political events that prevent customers from paying.

If you run into trouble with export requirements or other international trade questions, you can also contact the SBA’s Office of Manufacturing and Trade for guidance.

3. Ensure legal and regulatory compliance.

Before you open for business in another country, make sure you’ve covered your legal bases. Requirements vary widely, and overlooking something could lead to fines, delays or other expensive problems. Here’s what to do:

  • Research tax obligations and structures: Find out what corporate taxes, sales taxes or value-added taxes (VAT) you’ll owe, along with any rules about transactions between related companies. Check whether tax treaties with the U.S. apply to your business. You’ll also need to decide whether to establish a subsidiary, branch or representative office, since each comes with different tax and legal considerations.
  • Secure necessary licenses and permits: Depending on your industry, you may need special licenses, import or export permits, professional certifications or other approvals before you can start operating. Find out what’s required early so you’re not stuck waiting for paperwork when you’re ready to launch.
  • Check anti-corruption laws and trade sanctions: U.S. laws still apply to many of your activities overseas. The Foreign Corrupt Practices Act prohibits certain payments to foreign officials to win or keep business, while the Treasury Department’s Office of Foreign Assets Control administers sanctions that can restrict dealings with particular countries, companies and individuals. If your business handles defense-related products or technology, you’ll also need to check whether the International Traffic in Arms Regulations apply.
  • Protect your intellectual property (IP): Don’t assume your U.S. trademarks and patents will protect you overseas. Research the local requirements for protecting your intellectual property, including registering trademarks and patents where necessary and understanding how copyright protections apply. You’ll also want to understand how the country handles IP disputes.
  • Understand employment and labor laws: Look into local hiring requirements, minimum wages, employee benefits, termination rules and worker protections. These can be quite different from what you’re used to in the U.S., and you’ll need to account for them when planning your staffing and payroll costs.
  • Stay on top of compliance requirements: Your responsibilities won’t end once you’ve opened your doors. Keep track of filing deadlines, reporting requirements and changes to local laws. Consider working with local attorneys and accountants who can help you stay compliant as your business grows.
Did You Know?Did you know

Some of the best business phone systems can help you regularly conduct effective video conference calls with your overseas teams. Remote meetings cost substantially less than overseas business travel.

4. Use PEST analyses to plan for the unexpected.

You can’t control everything that happens in a country where you do business, but you can prepare for some of the surprises. A PEST analysis looks at political, economic, social and technological factors that could affect your company. It’s a useful exercise before entering a new market, and worth repeating once you’re established there.

Here are a few ways to put PEST analyses to work: 

  • Keep an eye on what’s happening: Follow local news, economic conditions, regulatory developments and changes in consumer behavior. Industry associations, local business contacts and consultants can help you spot developments you might otherwise miss.
  • Prepare for different scenarios: What would happen if tariffs increased, the local currency lost value or a new competitor entered the market? Think through how these changes would affect your business and what you could do in response. Having a backup plan beats scrambling to come up with one when trouble hits.
  • Understand the risks in each country: Political instability, trade disputes and strained relations with the U.S. can put your overseas operations at risk. In extreme cases, governments may restrict foreign businesses, seize assets or impose sanctions that force companies to stop operating in a market. Consider how you would protect your employees, investments and business assets if conditions deteriorated.
  • Watch for opportunities, too: Changes in technology, consumer preferences and government policies can work in your favor. For example, growing internet access might make it easier to reach customers online, while changes in trade agreements could open up new markets. A PEST analysis can help you recognize these opportunities before your competitors do.

Organic global expansion vs. overseas acquisitions

Opening a business in another country takes time. You’ll need to hire employees, find customers and build a reputation, often without knowing how quickly sales will pick up. But there’s another way to enter a foreign market: Buy a business that’s already operating there.

An overseas acquisition can give you an established customer base, experienced employees and relationships with local suppliers and advisers. Of course, buying a company comes with its own headaches. You’ll need to make sure you’re getting what you pay for, and combining two businesses can be tricky, especially when they’re in different countries.

If you’re considering an overseas acquisition, bring in an attorney and accountant with international experience before making an offer. They can help you review the company’s finances, uncover potential legal problems and understand the tax implications of the purchase.

Here’s how the two approaches compare:

Factor

Organic expansion

Acquisition-based expansion

Speed to market

Usually takes longer to get established

Can provide a faster entry into an existing market

Initial investment

Costs can be spread over time as the business grows

Often requires a substantial upfront purchase

Control

You build operations and processes your way

You may inherit systems and practices you want to change

Risks

Uncertain demand and the challenge of attracting customers

Risk of overpaying, hidden liabilities and integration problems

Local knowledge

Must develop local expertise or hire people who have it

Existing employees and managers may provide valuable insight

Branding

Easier to maintain your existing brand identity

May need to decide whether to keep or replace the acquired brand

Customer base

Must attract customers and earn their trust

Gain an existing customer base, although some may leave after the acquisition

Company culture

Can establish your own workplace culture

Must manage differences between the two companies

Regulatory compliance

Must establish compliance procedures

Inherit existing procedures, which still need to be reviewed

Growth potential

Can build operations around your long-term plans

May gain immediate capacity but need to update existing operations

Exit strategy

May be able to scale back gradually, depending on commitments

Selling or closing the acquired business can be complicated

Organic expansion may make more sense if:

  • You have time to establish your business in a new market.
  • Maintaining your existing brand identity is important.
  • You want to build your overseas operations from the ground up.
  • You’d rather invest gradually than make a large acquisition.

An overseas acquisition may be a better option if:
  • You want to enter a new market relatively quickly.
  • You’ve found a company with valuable customers, employees or supplier relationships.
  • An established local presence would help you overcome barriers to entry.
  • You have the money and management resources to handle the purchase and integration.
Did you find this content helpful?
Verified CheckThank you for your feedback!
Mark Fairlie
Written by: Mark Fairlie, Senior Analyst
Mark Fairlie brings decades of expertise in telecommunications and telemarketing to the forefront as the former business owner of a direct marketing company. Also well-versed in a variety of other B2B topics, such as taxation, investments and cybersecurity, he now advises fellow entrepreneurs on the best business practices. At business.com, Fairlie covers a range of technology solutions, including CRM software, email and text message marketing services, fleet management services, call center software and more. With a background in advertising and sales, Fairlie made his mark as the former co-owner of Meridian Delta, which saw a successful transition of ownership in 2015. Through this journey, Fairlie gained invaluable hands-on experience in everything from founding a business to expanding and selling it. Since then, Fairlie has embarked on new ventures, launching a second marketing company and establishing a thriving sole proprietorship.