Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
Looking for funding? When banks let you down, consider an alternative loan.

While every business owner aims for growth, securing capital through traditional banks or the SBA isn’t always feasible due to strict requirements or slow processing times. For those needing faster, more flexible financing options, alternative lenders offer a path forward. This guide dives into the world of alternative lending, exploring common loan types and key lenders to help you find the perfect fit for your small business.
>> Read next: The Best Business Loan and Financing Options of 2026
Alternative lending refers to financing secured through non-bank institutions. These fintech companies and private lenders emphasize speed and accessibility over the rigid criteria used by traditional banks. Alternative loans tend to be more flexible than conventional loans, and they often have a faster application turnaround. Many types of alternative loans are available, so there is likely an alternative loan out there that suits your business’s needs.
Many banks and conventional lenders take weeks to process a loan application, but alternative lenders can deliver funding in a few days. The loan application process for alternative loans is often simpler, requiring only a credit score, tax returns, and bank statements.
“The alternative lending and fintech world moves a thousand times faster [than traditional banks],” said Nate Marshall, SVP and Regional Market Executive at Civista Bank. “The general offerings and quick money is good, but I don’t know how much they check to see if this is the right fit for a customer. A bank is more focused on our relationship and we’re in this together.”
Searching for funding and not sure where to start? Tell us a little more about your business and get customized quotes from qualified providers.
Alternative lenders also are more likely to offer loans in smaller amounts than banks, which often include minimum lending terms that are often too high for a small business. Furthermore, these lenders frequently provide asset-based financing, allowing companies to leverage accounts receivable or daily credit card sales rather than relying solely on creditworthiness.
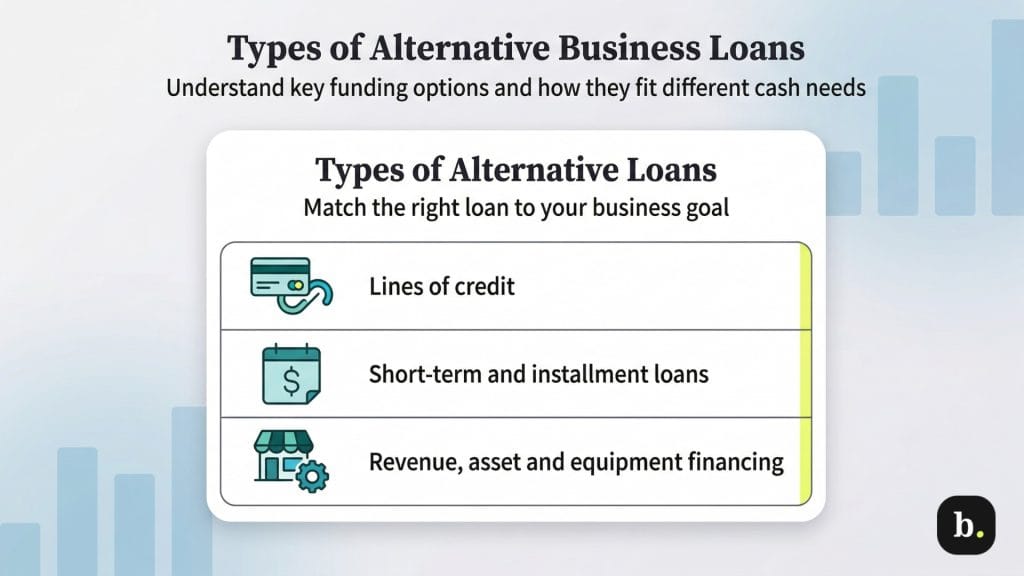
A business line of credit functions similarly to a credit card but provides access to actual cash. An alternative lender extends a fixed amount of money to the borrower. You can draw from the line of credit up to the fixed amount, paying interest on the amount you borrow.
Short-term loans are generally paid back in a year or less. Most banks don’t offer short-term loans, but they’re a common offering from alternative lenders. These loans are ideal for addressing immediate cash-flow gaps or covering emergency expenses, though they often carry higher annual percentage rates (APRs).
Installment loans provide a lump sum of money to a borrower, which is then repaid at regular intervals. Many installment loans from alternative lenders feature a fixed payment amount, which means the interest rate will not fluctuate during the life of the loan. Installment loans are commonly used to finance the purchase of real estate, vehicles, and the equipment a business needs to operate.
A merchant cash advance (MCA) offers a business funding in exchange for a cut of future sales. This financing option, based on future credit card receivables, can provide a quick infusion of cash up front. Instead of fixed monthly payments, the provider automatically deducts a percentage of your daily credit card sales until the advance, plus fees, is repaid.
Microloans, as the name suggests, are low-value loans — typically $50,000 or less. According to the U.S. Small Business Administration, the average microloan is approximately $13,000. Interest rates on SBA microloans typically range from 8 to 13 percent, depending on the intermediary lender. Since many banks don’t offer loans below a minimum funding threshold, alternative lenders can fill the gap for small-scale needs. Microloans often feature shorter repayment periods, sometimes as little as a few months.
Invoice factoring is a type of financing in which a business sells its outstanding accounts receivable to a third party (referred to as the “factor”) in exchange for a cash payment. Typically, a company receives about 80 to 95 percent of the invoice value immediately, with the remainder paid (minus fees) once the customer settles the bill.
A bridge loan is a short-term loan backed by a hard asset. If a business owner is moving from one location to another and is in the process of selling the first location, for example, they can use a bridge loan to purchase the new property and cover all closing costs. In this case, the new property would act as collateral for the bridge loan. These loans are typically very short-term, often taking less than a year to repay.
Equipment financing is used to purchase equipment your business needs to operate. Unlike general working capital loans, the equipment itself serves as collateral for the loan. This structure often results in more favorable approval odds and interest rates, as the lender assumes less risk.
[Find out about farm equipment loans.]

Before you apply for a business loan or alternative funding, think about what you need the cash for. If it’s to bankroll an expensive piece of equipment, a long-term loan or equipment financing may make the most sense. If you need to deal with a cash-flow issue or purchase more inventory, a short-term loan is better.
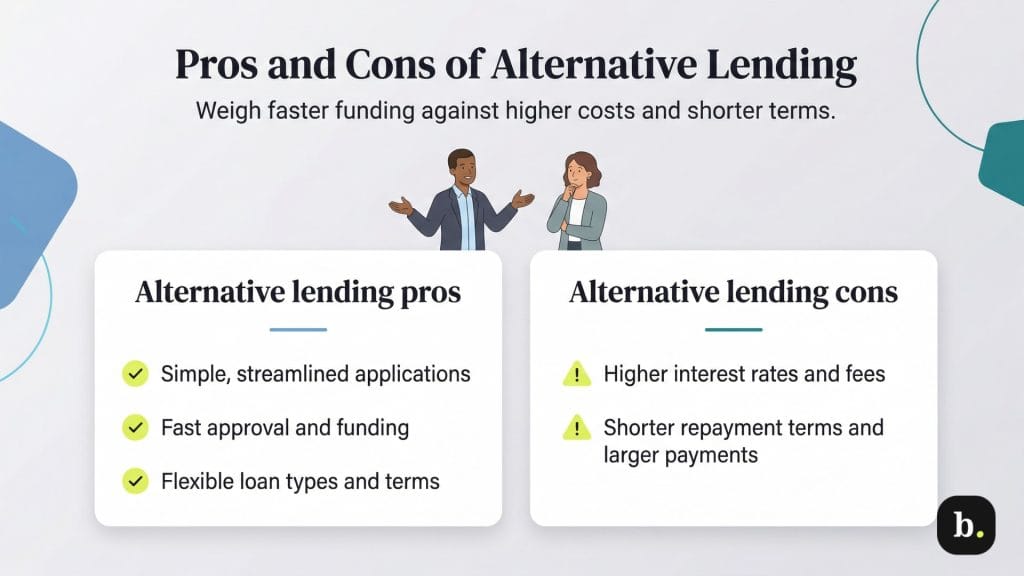
Alternative lending solutions offer some major advantages over bank loans and other conventional financing options. Here’s where alternative lenders outshine banks and credit unions.
Banks and credit unions naturally have their own advantages over alternative lenders. You may have to deal with the following issues if you choose an alternative lending option instead of a traditional bank loan.
When it comes to small business funding, alternative lenders are more willing than their bank counterparts to approve a loan. With any financing provider, however, it’s critical to understand the fine print of your loan agreement before signing on the dotted line.
The cost of alternative lending depends on the loan terms and the provider. Depending on the lending source, you may be subject to an annual percentage rate (APR). Some lenders may charge a monthly fee or factor rate for the loan instead, which is beneficial for those who plan on quick repayment but can be expensive if the debt drags on.
If, however, the lender charges an APR that seems low, confirm the fees associated with the loan. The lender, for example, may charge an organization fee, which represents the expense of processing your loan and may cost upward of 3 percent of the loan amount. Other lenders may charge a set dollar amount for closing costs. During the loan negotiations, ask for a breakdown of the total loan costs to understand what you’ll be paying in full to borrow the money.
Alternative lending isn’t necessarily better than traditional lending, but it offers distinct advantages. Primarily, alternative lending provides the opportunity for small and midsize businesses to harness funding when they may not qualify for traditional loans. Alternative lending also provides more flexibility, including faster processing and shorter payment terms.
Alternative lenders are also more versatile than traditional lenders in the amounts they can provide to businesses. In some cases, businesses borrow a moderate amount from an alternative lender in addition to a standard bank loan. Another benefit of alternative lending is the industry relies on risk assessments beyond a credit score to approve loans. If any of those scenarios or needs apply to your circumstances, then alternative lending may be the better option for your business.
Alternative lending began in the early 2000s. The first alternative lenders entered the marketplace around 2005. Companies specializing in peer-to-peer loans are credited with launching the trend, though the definition has expanded significantly since then. Alternative lending companies started out to aid small and midsize businesses due to banks’ preference for funding corporations, which they consider less of a financial risk, instead of smaller enterprises.
Yes, you can likely get an alternative loan with bad credit. Some lenders even specialize in providing lending options to those with bad credit. Instead of looking at a credit score, the lenders will consider qualifications such as your company’s minimum annual revenue. The alternative lender also usually weighs the applicant’s experience. The lender, for instance, may request that applicants have operated their business for at least a year before applying. That longevity may indicate your worthiness to the provider even if your credit score doesn’t.
Mike Berner and Adam Uzialko contributed to the reporting and writing in this article. Source interview was conducted for a previous version of this article.