Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
A Roth IRA is one of the most crucial retirement savings tools self-employed professionals need in their arsenal.
Today’s American workforce is increasingly nontraditional, with more professionals freelancing, owning businesses and working as independent contractors. In fact, according to Small Business Administration (SBA) data, about 81 percent of small businesses have no employees beyond the business owner. With self-employment growing more popular and commonplace, retirement planning is a pressing concern for people in these situations. However, a Roth individual retirement account (IRA) may be an excellent solution for self-employed individuals seeking a potent retirement strategy. We’ll explain more about Roth IRAs and what self-employed people need to know about this type of retirement account.
Searching for employee retirement plans and not sure where to start? Tell us a little more about your business and get customized quotes from qualified providers.
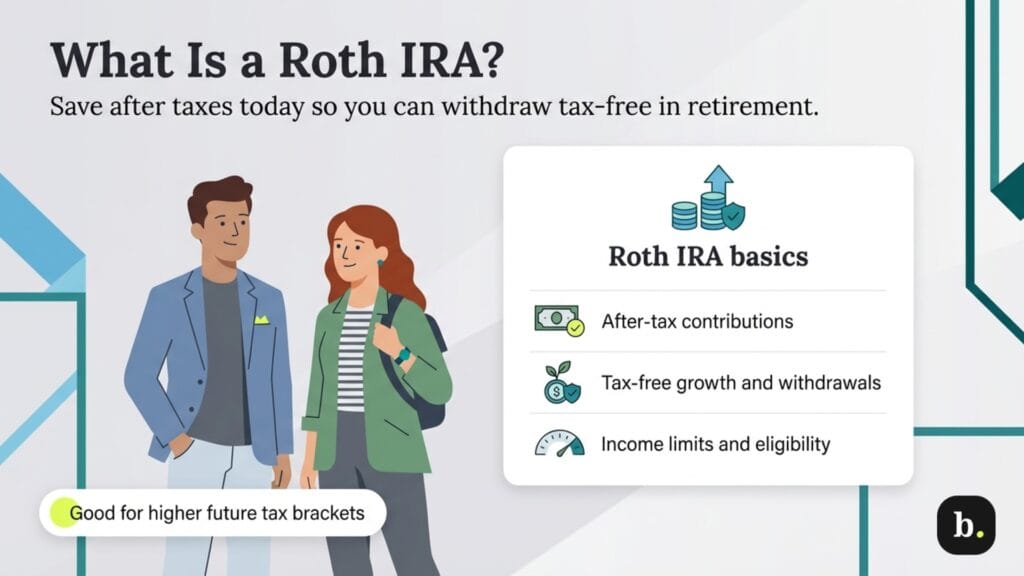
A Roth IRA is a type of retirement account that allows individuals to contribute after-tax dollars. The money grows tax-free and account holders can access funds in their account once they turn 59½ without paying any taxes on their distributions.
Roth IRAs are particularly helpful for people who expect to be in a higher tax bracket in retirement, including many self-employed individuals and small business owners who might sell or cash out of their companies later in life.
However, not everyone is allowed to use a Roth IRA. Your modified adjusted gross income must be under specific limits, which vary from year to year and are based on your tax filing status.
Some of the ways traditional and Roth IRAs differ include when you pay taxes on your retirement account and whether you can take early withdrawals.
With traditional retirement savings plans, people can deduct contributions from their taxes but must pay taxes on withdrawals. In contrast, Roth plans require you to contribute after-tax money but allow you to deduct withdrawals you make in retirement.
For self-employed individuals and small business owners, choosing the right retirement account is especially important since there’s no employer match or automatic enrollment to fall back on. Understanding the tradeoffs of a Roth IRA can help you make a more strategic decision.
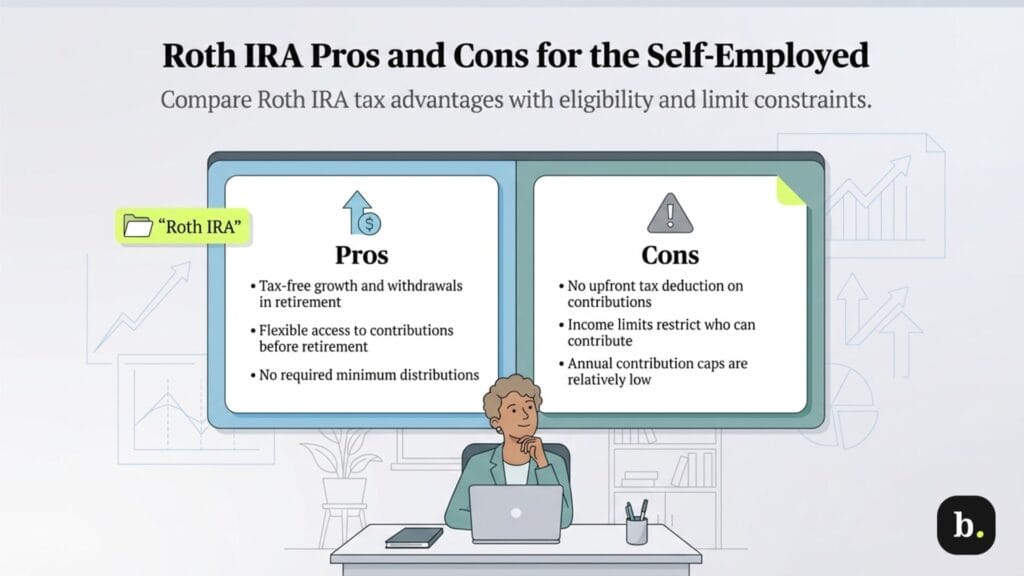
Roth IRAs bring the following benefits, which may be of particular interest to self-employed individuals and business owners:
While Roth IRAs offer tax-free growth and tax-free distributions, they also have several drawbacks, including the following:
Self-employed individuals should also research Simplified Employee Pension (SEP) IRAs and other self-employed retirement plans designed with their unique needs in mind.
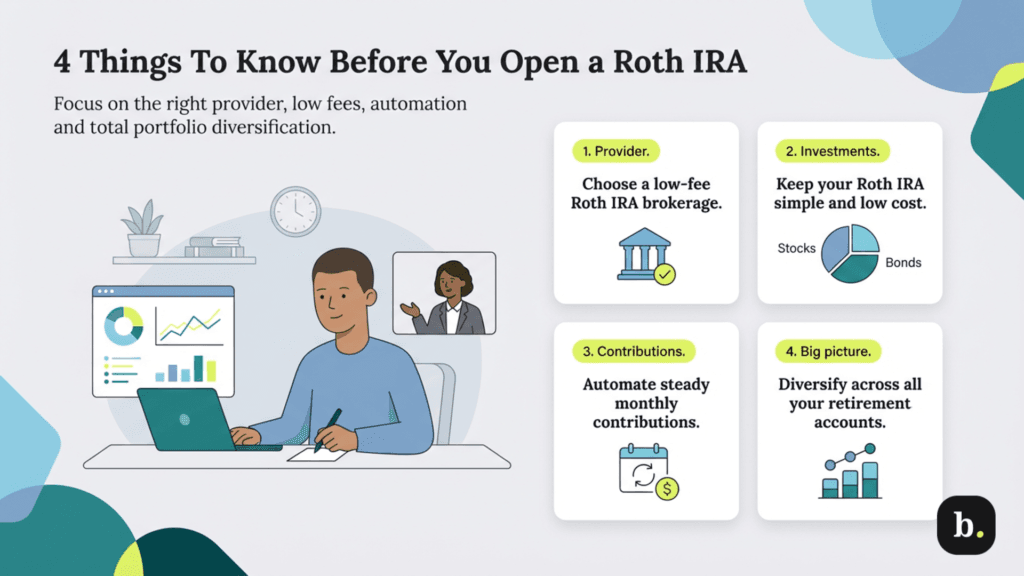
If you’re seriously considering opening a Roth IRA, keep the following in mind.
Both well-known and smaller brokerage houses offer Roth IRAs as options. Here are some tips for selecting a brokerage company to hold your Roth IRA:
The best employee retirement plan providers offer ample plan options, reasonable costs, low investment fees, and solid advice and customer support.
One of the easiest options is a high-quality target date fund, which will automatically match your investment mix to your age as the years go by. You can also ask your brokerage to buy a selection of mutual funds or exchange-traded funds (ETFs). The classic approach is a mixture of stock and bond funds, with the proportion of bond funds rising as you age.
One of the factors you can best control is fees. Look for low fees on whatever investment you pick. You should be able to find low-fee, broad-based index funds for your Roth IRA with an expense ratio well under 0.20 percent a year — some funds from major providers now charge as little as 0.03 percent. Remember, any gains are growing tax-free; that’s one of the best things about a Roth IRA for the self-employed.
Be aware that contribution limits for tax-qualified accounts like IRAs are not considered separately. If you contribute money to a Roth IRA, you can’t contribute the maximum to other types of IRAs.
Unlike traditional employers, self-employed professionals don’t have the crutch of automated deductions and escalations. It’s best to set up monthly automatic deductions from your bank account to your Roth IRA. Small, regular contributions over time can help your returns. “Small, consistent contributions not only help with discipline but also take advantage of dollar-cost averaging,” Munchow said.
When it comes to retirement funds for solopreneurs and other self-employed individuals, it’s crucial to note that you are solely responsible for ensuring that your retirement accounts are diversified into stock and bond funds — perhaps international stock and bond funds, too.
Why is it crucial to look at all your plans at once? If you’re 90 percent in stock mutual funds in your SEP plan, which has $100,000, and 90 percent in bond funds in your Roth, which has only $25,000, you aren’t properly diversified between stocks and bonds. Look at your total and then decide how you want to invest.
The most significant difference between SEP and Roth IRAs is that SEPs have much higher contribution limits. In 2026, a SEP IRA allows you to deposit up to 25 percent of your net self-employment income, up to $72,000 annually. Unlike Roths, SEPs are taxed as regular income during retirement. However, you can make pretax contributions to a SEP. Essentially, a SEP allows the taxes you owe on it to be deferred until retirement. With a Roth, you pay taxes on the income upfront. In 2026, you can contribute $7,500 to a Roth after making your SEP contribution ($8,600 if you are 50 or older). However, you also must fall under the income limit for Roths. If you are married filing jointly, your ability to contribute phases out beginning at $242,000 and is eliminated at $252,000. The ability to contribute to both a SEP and a Roth is a boon to the self-employed that makes it a little bit easier to save. Detailed rules are available on the IRS website.
A 401(k) is another option for self-employed workers saving for retirement. With small business 401(k) plans, you can salary-defer up to $24,500. If you are over 50, you can add another $8,000. As of 2026, those aged 60 through 63 can make an even larger catch-up contribution of up to $11,250 under SECURE 2.0 Act provisions. You can also deposit up to 25 percent of your net earnings from self-employment, up to a total of $72,000, including salary-deferred payments.
It depends on your situation. For example, if you earn too much money to open a Roth IRA and want to contribute as much money as possible, a 401(k) is the better choice. However, if you prefer having the option to access your funds before retirement or think you may want to keep the money in the account after you turn 72, a Roth IRA might be the way to go. Some entrepreneurs opt to have both a Roth IRA and a 401(k) to diversify their retirement plans. “Having multiple retirement vehicles gives you flexibility in managing taxes and cash flow,” Munchow said. “Roth IRAs, in particular, give you the option to avoid required minimum distributions and optimize income in retirement.”
Assuming you make the maximum annual contribution of $7,500 each year for the next 10 years, you could accumulate over $108,000 with an approximate 8 percent average annual growth rate. Keep in mind this is a hypothetical scenario — actual growth will vary based on market performance, any changes to the contribution limit and whether you make full contributions every year.
Once you make the first contribution to your Roth IRA, you must wait five years before being able to withdraw your earnings tax-free. The five-year period begins on January 1 of the year you made your initial contribution.
Nathan Weller and Dock Treece contributed to the reporting and writing in this article. Source interviews were conducted for a previous version of this article.