Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
Why Small Businesses Need Online Payment Apps
Fewer people are relying on cash and want to use different methods, like online payment apps, to purchase items.
Business.com earns commissions from some listed providers. Editorial Guidelines.
Table of Contents
Small businesses that accept online payment apps like Apple Pay and Google Pay fare better than those that don’t. Offering customers their choice of payment methods can increase sales and put your small business at a competitive advantage. Read on to learn more about the benefits of accepting online payment apps.
What are online payment apps?
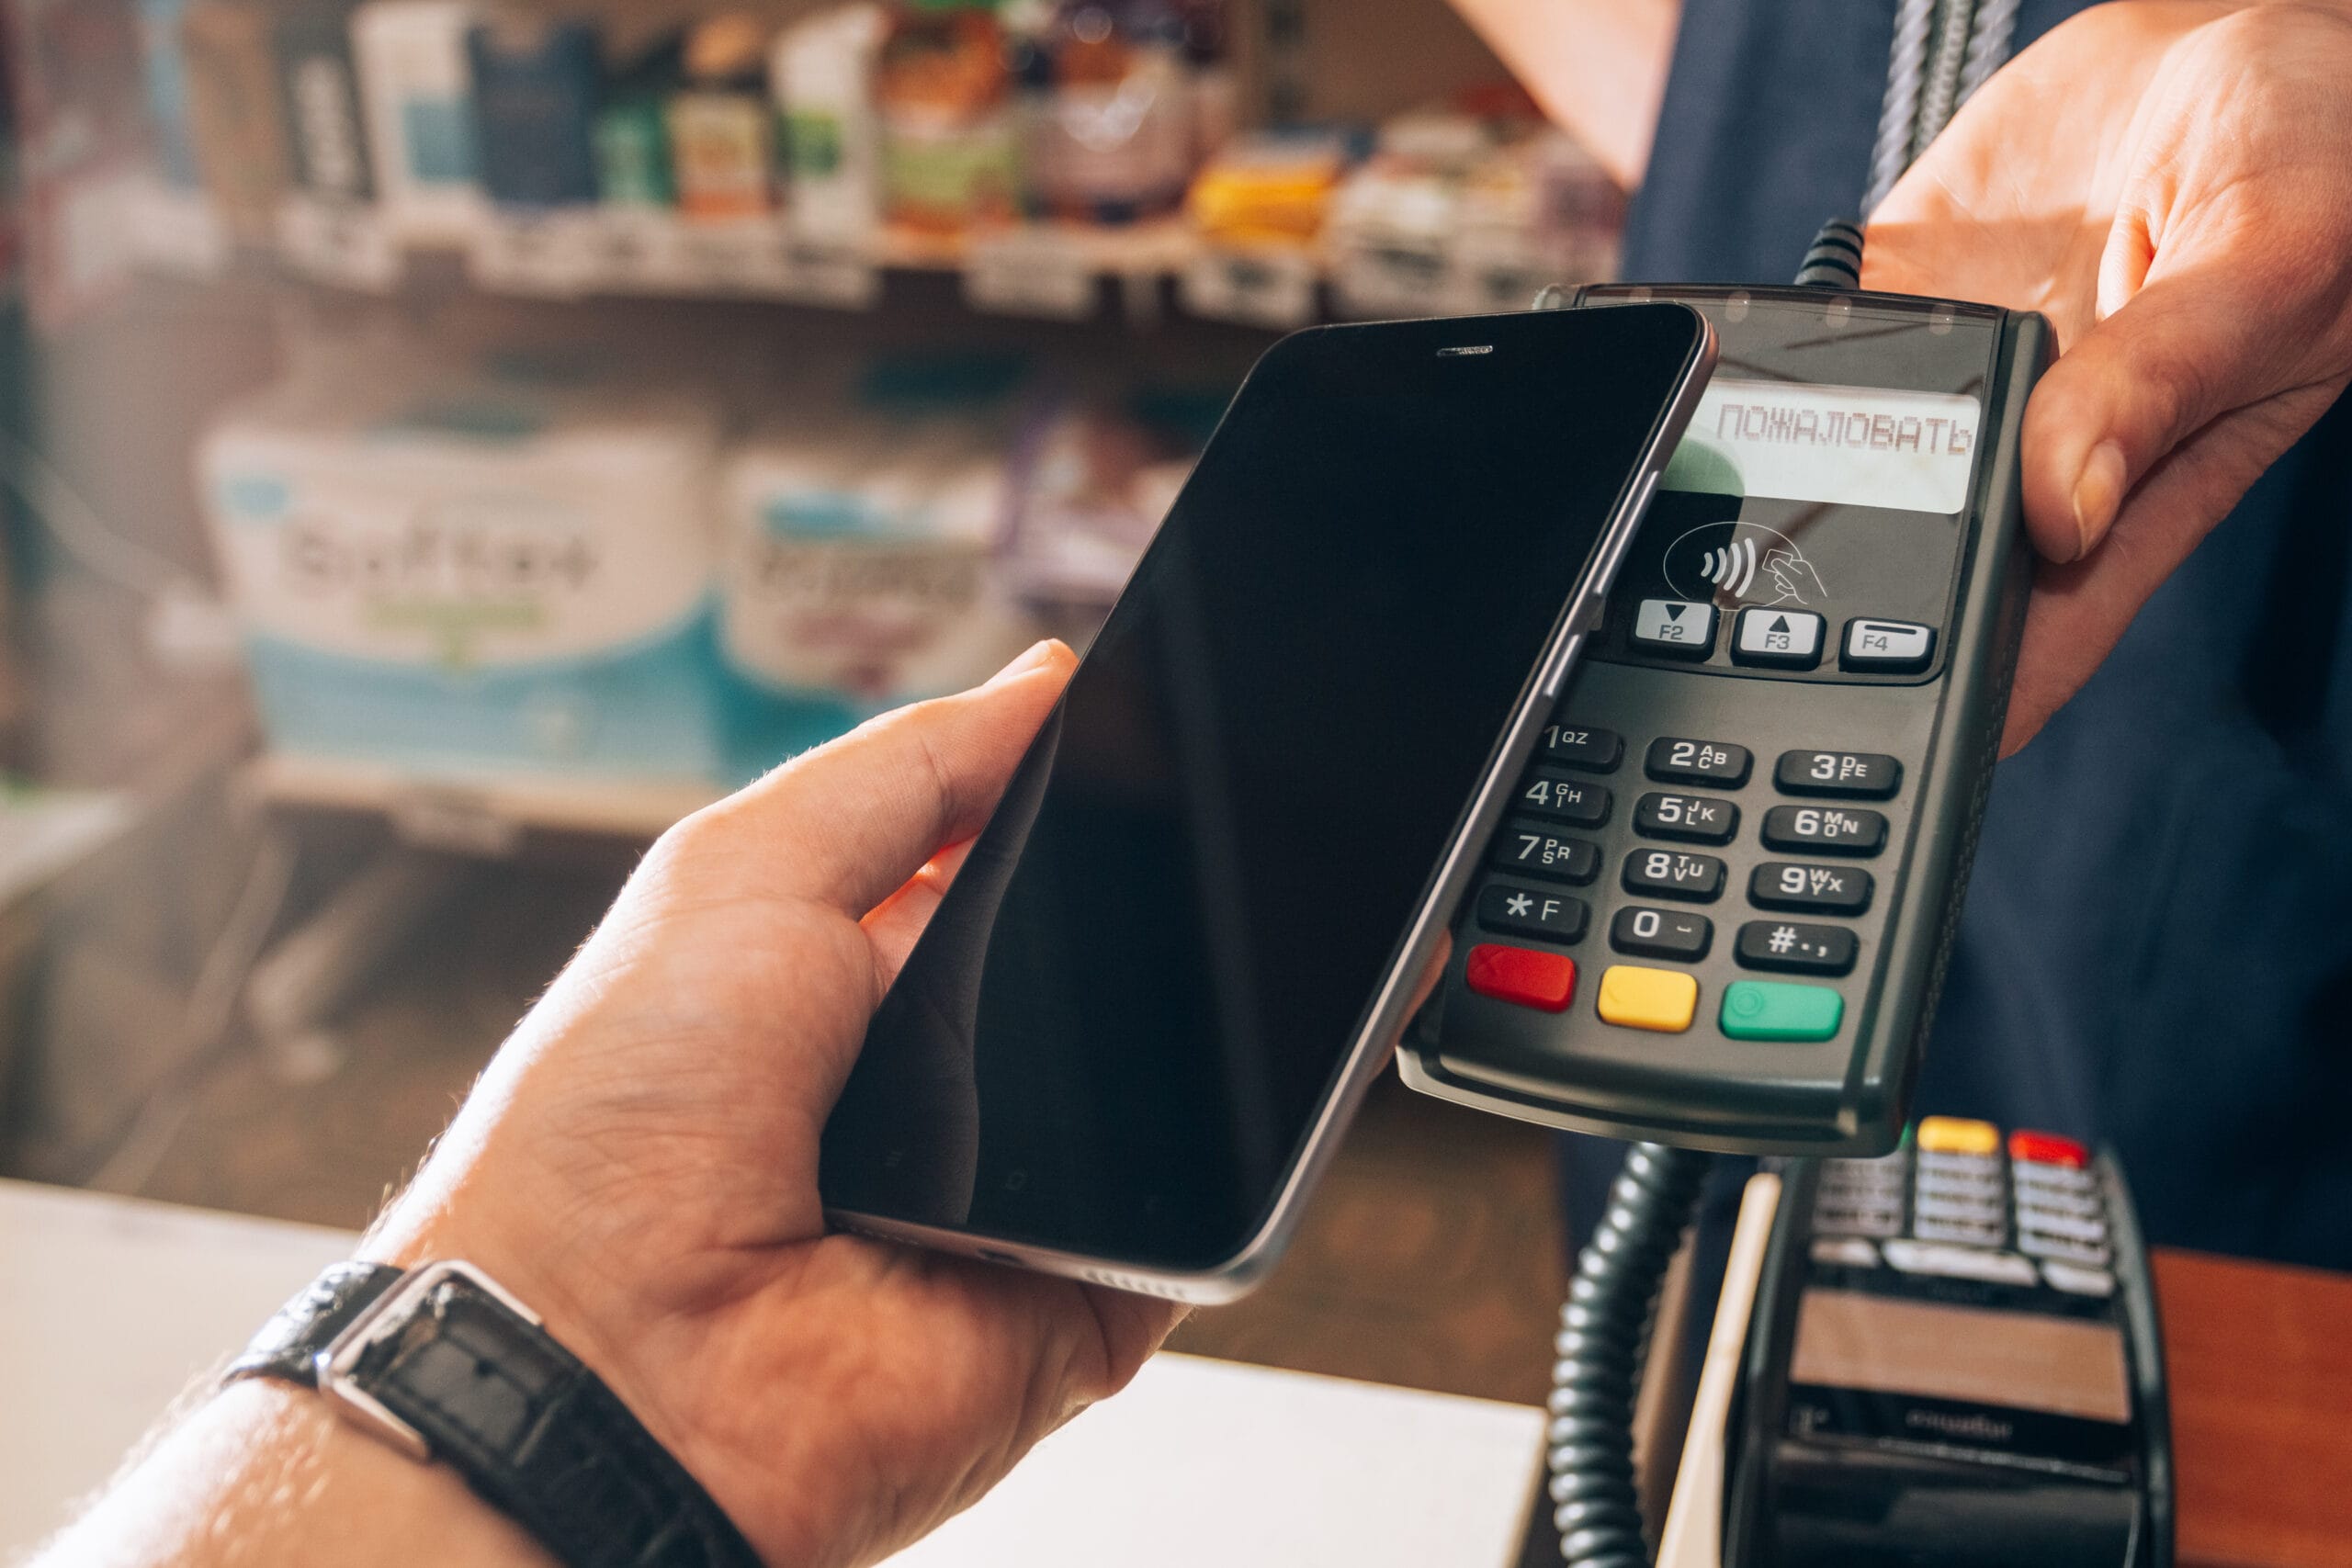
Online payment apps are digital wallets that securely store a user’s credit card or debit card information. To use one, a customer can open the mobile app on their phone or select the app option at checkout on a merchant’s website.
“Digital payments have become far more accepted,” David Axler, chief executive officer at Occupier, told us. “It’s become a part of our daily routine.”
What are the pros and cons of payment apps?
Online payment apps are easy to use and convenient, but they aren’t risk free. Here’s a look at the pros and cons of accepting online payment apps in transactions with your customers.
Pros of online payment apps
They’re a familiar payment method. Consumer comfort with digital payments has grown steadily, and the numbers reflect it. Precedence Research values the overall digital payments market in the United States at approximately $170.24 billion in 2025, a figure projected to surpass $790.59 billion by 2035. “It speaks to the comfort level of consumers in paying online,” Axler said. “It used to be not well understood, not routine.”
They’re convenient for customers. Many customers like the convenience digital wallets offer, allowing them to cycle through various payment methods at will. When a business accepts online payment apps, customers know they can choose to pay however they like, which helps improve customer satisfaction and build loyalty.
They speed up checkout. Accepting online payment apps streamlines the checkout process in both e-commerce and brick-and-mortar stores. The quicker and easier it is to purchase something, the less likely a customer is to abandon their shopping cart.
They improve security. Digital wallets tokenize card details, replacing credit card numbers with unique and random codes called “tokens.” Tokenization improves security and reduces the likelihood that data breaches expose customers’ financial information. This creates peace of mind for customers and reduces potential liability on the part of the business by reducing the amount of sensitive data they keep on hand.
FYI
In the U.S., 92 percent of adults use digital payments, McKinsey recently reported. The firm also found that in-store digital wallet use increased significantly, with 1 in 5 digital wallet users now leaving home without a physical wallet.
Cons of online payment apps
Scammers target digital wallets often. Scammers often target consumers and businesses using online payment apps. For instance, dummy apps that appear in the online app stores collect personal information about the user and use it to commit fraud. Encourage your customers to use well-known payment apps available from legitimate vendors.
They can get pricey to accept. You’ll be charged a transaction fee when customers use payment apps linked to their credit cards. Card-not-present payments, which is the category online payments often fall under, typically cost more for the merchant. “It tends to be the most expensive way to go,” said Andi Gray, president of Strategy Leaders. “Business owners really need to know what they need the payment app for.”
They’re harder to manage. Getting all the transactions from disparate payment apps into one accounting system can be cumbersome and time-consuming. “When you start to accept payments electronically, you don’t have them tied to a particular invoice or particular receipt,” Axler said. Business owners can address this challenge with cloud-based accounting software that consolidates all transactions under a single dashboard. [Read related article:The Best Accounting and Invoice-Generating Software]
Did You Know?
By 2030, 70 percent of global consumers will use digital wallets, up from 55 percent in 2025, according to Capital One Shopping Research.
The best online payment apps
These are the best online payment apps that small businesses should consider accepting:
Apple Pay: Apple Pay is among the best-known mobile payment apps. Users input their credit or debit card information into the mobile wallet on their iPhone and then they can use Apple Pay in stores and online. Apple Pay uses near-field communication (NFC) technology to enable contactless payments. There is no fee to accept Apple Pay, but you do pay the transaction fees on credit card and debit card sales. [Read related article:How to Accept Payments With an iPhone]
PayPal: PayPal is a popular online payment app for consumers in America and abroad. It’s free to use and accept, but you’ll pay rates of about 3.49 percent + $0.49 per transaction. You can also send invoices to clients through PayPal’s online platform. [Find out more aboutcredit card processing with PayPal]
Venmo: This popular peer-to-peer payment app is owned by PayPal and has more than 90 million active accounts. There are no fees to use or accept Venmo, although it generally charges transaction rates of 1.9 percent plus $0.10 for payments via credit or debit card. You get paid instantly when a customer uses Venmo. [Find out howVenmo Businessworks and how to get it for your company]
Zelle: This online payment app lets you accept payments directly from customers’ bank accounts, including Bank of America, JPMorgan Chase, Wells Fargo, Capital One and U.S. Bank. Generally, there is no fee to send or receive money with Zelle as either a business or consumer. However, users’ banks may set transaction limits and fees. Your business account needs to be registered with Zelle before you can accept payments.
Google Pay: Google Pay remains a widely used digital wallet option for Android and iPhone users alike, making it a versatile choice for small businesses looking to broaden their payment acceptance. You won’t be charged any fee for taking payment by Google Pay, but expect to be charged as usual by your payment processor. [Related article:Android credit card payment app][Related article:SMB Payment Processing: What to Know]
Mark Fairlie and Jennifer Dublino contributed to the writing and reporting in this article. Source interviews were conducted for a previous version of this article.
Donna Fuscaldo, who has 25 years of experience navigating the convergence of business, finance, and technology, is a trusted advisor to small business owners. Her expertise in business borrowing, funding, and investment strategies equips her to provide reliable counsel on everything from business loans to accounting and retirement benefits.
At business.com, Fuscaldo covers business grants and other financing options, business credit cards and retirement funds.
Her analysis has also graced publications like The Wall Street Journal, Dow Jones Newswires, Bankrate, Investopedia, Motley Fool, Fox Business and AARP, solidifying her authority in the field. Beyond her contributions to the financial landscape, Fuscaldo also lends her wisdom on employment matters, with her expertise sought after by platforms like Glassdoor and others.
Armed with a bachelor's degree in communication arts and journalism, Fuscaldo has the unique ability to simplify complex business and career-related topics into actionable insights. This makes her a valuable resource for professionals seeking practical solutions in today's dynamic business environment.
Armed with a bachelor's degree in communication arts and journalism, Fuscaldo has the unique ability to simplify complex business and career-related topics into actionable insights. This makes her a valuable resource for professionals seeking practical solutions in today's dynamic business environment.