Your free business.com+ membership unlocks exclusive tech deals and advisor support
Join Free
BDC Hamburger Icon

Menu

Close
BDC Logo with Name
Search Icon
Search Icon
Advertising Disclosure
Close
Advertising Disclosure

Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.

As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.

What Are the Benefits of a Section 125 Plan?

Section 125 plans can help employees save on taxes while making certain workplace benefits more affordable.

MIranda Fraraccio
Written by:
Miranda Fraraccio, Senior Writer
author image
Editor verified:
Gretchen Grunburg,Senior Editor
Last Updated Oct 26, 2026
Business.com earns commissions from some listed providers. Editorial Guidelines.
Table Of Contents Icon

Table of Contents

Open row

Offering a great employee benefits package can help businesses retain talent and boost employee engagement. But with health insurance costs continuing to rise, employers are looking for ways to make benefits more affordable. One option worth considering is a Section 125 plan, also known as a cafeteria plan. It allows employees to pay for certain benefits with pretax wages, reducing their taxable income. Employers may also save on payroll taxes.

We’ll explain what a Section 125 plan is, how it works and how to set one up so you can decide whether it’s right for your team.

What is a Section 125 plan (cafeteria plan)?

A Section 125 plan is a written, employer-sponsored benefits plan that allows employees to use pretax wages to pay for certain benefits instead of receiving that money as taxable income. It’s also called a “cafeteria plan” because employees can pick and choose from the benefits their employer offers.

For example, employees can use a Section 125 plan to pay their share of eligible health insurance premiums with pretax wages. They can also set aside pretax money in a health flexible spending account (FSA) to cover qualifying medical expenses. In both cases, employees generally save on federal income taxes, as well as Social Security and Medicare taxes. State and local tax rules vary.

As with most employee benefit plans, participation in a Section 125 plan is optional. Some employees may opt out and simply receive their full taxable wages instead. However, for many employees, setting aside money before taxes are deducted can be the more advantageous choice.

“Section 125 plans are a good way to help workers control health care costs, which have been outpacing inflation for decades, so they definitely provide value at a low cost to companies,” explained Hayden Cohen, CEO and co-founder of staffing and recruiting agency Near.
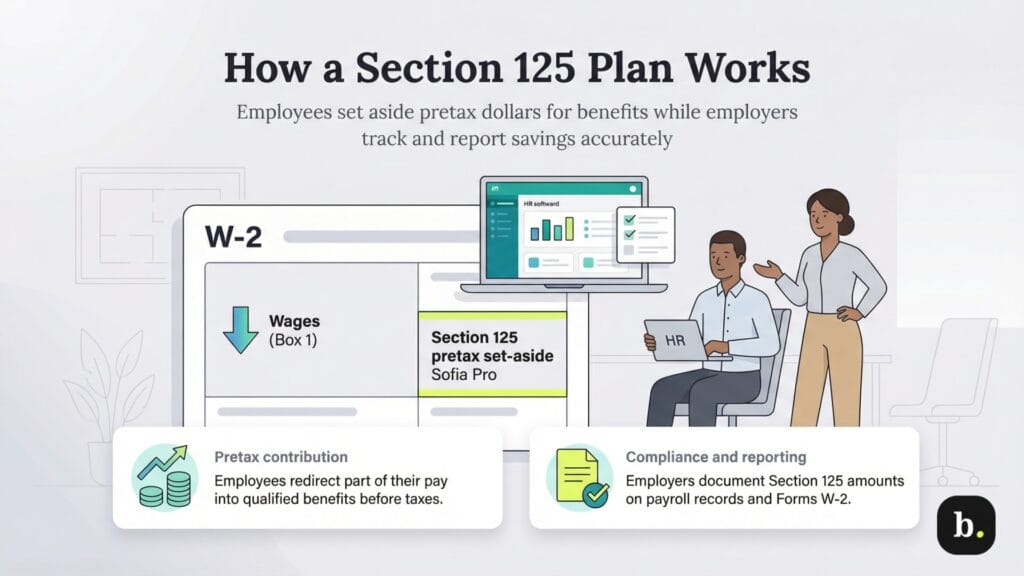
How does a Section 125 plan work?

section 125 plan
A diagram illustrating how pretax contributions flow into a Section 125 plan.

Section 125 plans are relatively straightforward. Here’s how they generally work:

  • Employees choose their benefits. Employees select from the eligible benefits their employer offers and agree to have the costs deducted from their pretax wages.
  • Employers handle the deductions. The employer uses those deductions to pay for eligible benefits, such as health insurance premiums or contributions to a health FSA.
  • Employees save on taxes. Because the money goes toward qualifying benefits instead of being paid as wages, employees generally pay less in federal income taxes and Social Security and Medicare taxes.

Employees typically make their benefit elections before the plan year begins. Changes during the year are generally limited to circumstances allowed by the plan and IRS rules, such as getting married, having a child or experiencing a change in employment status. Health savings account (HSA) contribution elections have more flexible rules.

Employers also need to account for these deductions on the appropriate tax and payroll forms. For example, if an employee puts $1,000 of their pretax wages into a health FSA, that money generally won’t be included in the taxable wages shown in Box 1 of their W-2. Other benefits may need to be reported differently.

Employers can manage these plans themselves or work with outsourced professionals. Cohen recommends using a qualified specialist, such as a professional employer organization (PEO) or HR outsourcing provider, to ensure expert benefits management and administration.

“A third-party administrator… [will] be able to handle reimbursements and make sure you’re documenting everything you need to be in order to stay compliant,” Cohen explained.
TipBottom line
When comparing the best HR software, ask whether the provider supports your specific benefits and payroll deductions, and whether plan documents, claims processing and compliance testing require a separate administrator.

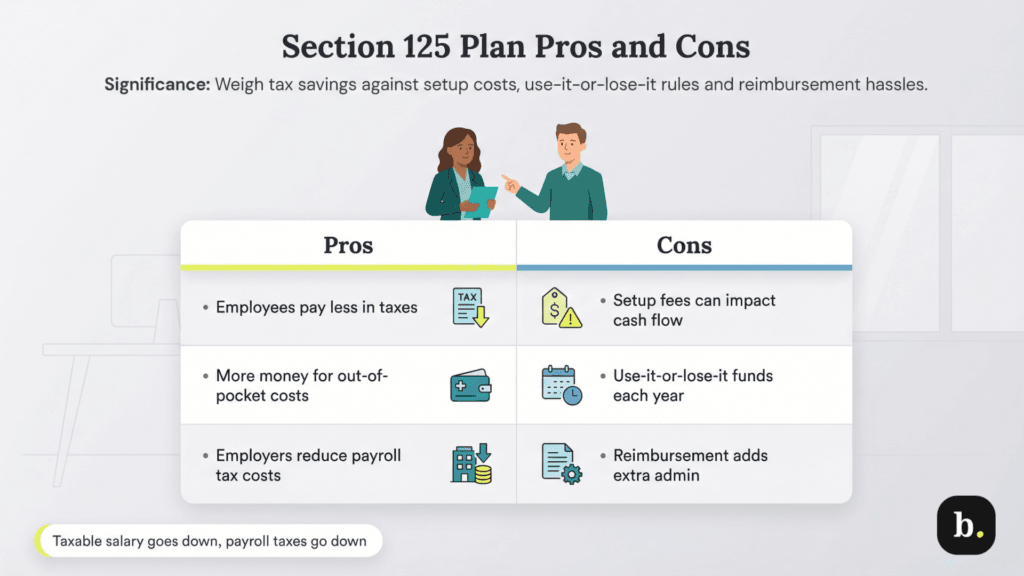
Section 125 plan pros and cons

section 125 pros and cons
A chart detailing the advantages and disadvantages of Section 125 plans for employers and employees.

Section 125 plans offer benefits for both employees and employers, but they also come with trade-offs.

Pros

Both employers and employees can benefit from Section 125 plans:

  • Employees can save on taxes: Money contributed toward qualifying benefits generally reduces employees’ federal taxable income. Depending on the benefit and where employees live, they may also save on Social Security, Medicare and state and local income taxes.
  • Employees keep more money for qualified expenses: Say an employee puts $5,000 in pretax wages toward benefits such as health insurance premiums and FSA expenses. They can use that money to cover eligible costs without first paying income taxes on it. If the same $5,000 were paid as regular wages, taxes would reduce the amount available to spend.
  • Employers pay less in payroll taxes: Employers can also save on payroll taxes when employees use pretax wages for qualifying benefits. For benefits exempt from both Social Security and Medicare taxes, employers can save 7.65 percent on wages subject to both taxes. Actual savings depend on the benefit and the employee’s earnings. 

“Offering a Section 125 cafeteria plan could provide businesses a competitive edge by offering their employees benefits while also reducing payroll taxes,” explained Brittany Truszkowski, SHRM-SCP and chief operating officer of Grand Canyon Law Group.

Cons

However, there are some drawbacks to consider with Section 125 plans:

  • Section 125 plans have setup and administrative costs: Employers may have to pay for plan documents, nondiscrimination testing and ongoing administration. Costs vary depending on the plan’s complexity, with premium-only plans generally costing less than plans that include FSAs. These expenses can be challenging for startups or businesses with cash flow problems, although payroll tax savings may help offset them.
  • Employees could lose unused FSA funds: Health FSAs generally follow a “use it or lose it” rule. Employers can allow employees to carry over a limited amount or give them a grace period to spend unused funds, but not both. They can also choose to offer neither. Dependent care FSAs don’t allow carryovers, although some plans offer a grace period. Money in an HSA, however, stays in the employee’s account.
  • FSAs require claims administration: Employees must use health and dependent care FSA funds for eligible expenses and may need to submit receipts or other documentation. Even plans that offer payment cards may require additional paperwork.
  • Employers take on some financial risk: With a health FSA, employees can access their full annual election before they’ve contributed the entire amount. If an employee uses more than they’ve contributed and then leaves the company, the employer generally has to cover the difference.
Did You Know?Did you know
Paying less in Social Security taxes today can also mean lower Social Security benefits in retirement, depending on an employee's earnings history.

Who can open a Section 125 plan?

Most employers can offer a Section 125 plan, including C corporations, S corporations, partnerships, limited liability companies, sole proprietors and tax-exempt organizations. Government entities can also offer these benefits to their employees.

However, business owners aren’t always eligible to participate in their own plans. Sole proprietors, partners and shareholders who own more than 2 percent of an S corporation generally can’t participate. Certain family members of those S corporation shareholders may also be ineligible. C corporation owners who work as employees can generally participate, while eligibility for LLC owners depends on how the business is taxed.

You’ll also need to determine which employees qualify for coverage, as eligibility depends on the plan’s rules, and there may be different requirements for full-time and part-time employees.

Simple cafeteria plans for small employers

Smaller businesses may qualify for a simple cafeteria plan, which makes it easier to meet certain IRS nondiscrimination requirements. Generally, employers with an average of 100 or fewer employees during either of the two preceding years are eligible.

These plans have their own rules. Employees who worked at least 1,000 hours during the previous plan year generally must be eligible, although employers can exclude certain groups, including employees under 21 or with less than one year of service. Employers must also contribute toward qualified employees’ benefits, with one option requiring at least 2 percent of compensation. A benefits administrator can help determine whether your business qualifies and what contributions are required.
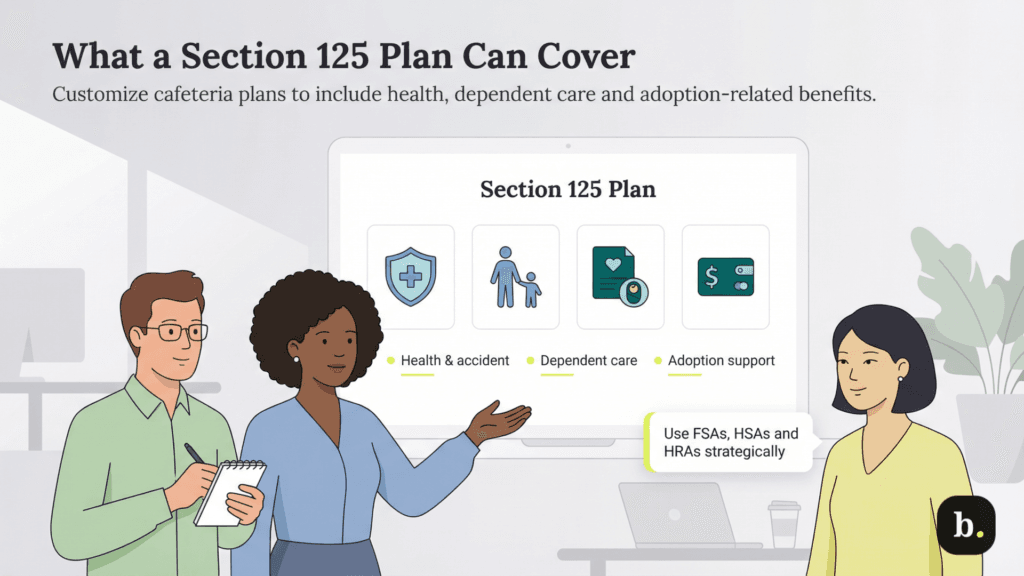
What does a Section 125 plan cover?

section 125 coverage

Employers must document in writing which benefits their Section 125 plan includes, who is eligible and how employees can select coverage.

“Section 125 plans are flexible in terms of what kinds of benefits are covered, but you do have to specify those benefits when you set up your company-wide plan,” Cohen advised. “Just because something like adoption assistance could be covered under Section 125 doesn’t mean that it will be unless you set it up.”

According to Section 125 of the Internal Revenue Code, cafeteria plans can include the following qualified benefits:

  • Accident and health benefits: These typically include employer-sponsored medical, dental and vision insurance. However, long-term care insurance and Archer medical savings accounts aren’t eligible.
  • Health FSAs: Employees can set aside up to $3,400 in pretax wages for 2026, provided their plan allows it. They can use the money for qualifying medical expenses, such as deductibles, copayments and other out-of-pocket costs, but not health insurance premiums.
  • Dependent care assistance plans (DCAPs): These plans help employees pay for care that allows them to work or look for work. Qualifying dependents generally include children under 13 and spouses or dependents who can’t care for themselves. For 2026, employees can exclude up to $7,500 in qualifying assistance, or $3,750 if married filing separately. Married couples filing jointly share the $7,500 limit, and additional eligibility and income rules apply.
  • Adoption assistance: Employers can help cover qualifying adoption expenses, subject to annual limits and income restrictions. These benefits may be exempt from federal income taxes but are generally still subject to Social Security and Medicare taxes. Regular wages paid during adoption leave don’t automatically qualify.
  • Group-term life insurance: Employers can offer this coverage through a cafeteria plan, although employees generally owe taxes on the calculated cost of coverage above $50,000. Special rules also apply to certain employees and plans.
  • HSAs: Eligible employees can contribute pretax money to an HSA to pay for qualifying medical expenses. For 2026, the contribution limits are $4,400 for individual coverage and $8,750 for family coverage, including employer contributions. Employees age 55 and older can contribute an additional $1,000. HSA eligibility depends on the employee’s health coverage and other factors, and unused funds carry over from year to year.

There are a few additional rules worth knowing:

  • FSA funding works differently depending on the account. With a health FSA, employees generally have access to their full annual election from the start of their coverage period, even before they’ve contributed that amount. Dependent care FSAs generally reimburse expenses only up to the amount already contributed.
  • Not all FSAs work with HSAs. Employees with a regular health FSA generally can’t contribute to an HSA, but a limited-purpose FSA covering dental and vision expenses won’t create the same problem.
  • Health reimbursement arrangements (HRAs) have separate rules. Employers must fund HRAs themselves, rather than through employee salary reductions. However, employees enrolled in an individual coverage HRA (ICHRA) may be able to pay their share of eligible individual health insurance premiums with pretax wages if they purchase coverage outside a government Marketplace.
FYIDid you know
Many of the best PEO services can help you manage FSAs, HSAs and other employee benefits. Just be sure to ask what's included in their services and whether you'll need a separate administrator for your Section 125 plan.

How to start a Section 125 plan

Setting up a Section 125 plan takes some planning, especially when it comes to choosing benefits, handling payroll deductions and meeting IRS requirements. Here are the steps to follow:

  1. Put your plan in writing. Before you start making pretax deductions, document which benefits you’ll offer, who’s eligible, when employees can enroll and how they can change their elections. If you’re offering FSAs, include any carryover or grace period rules.
  2. Explain the benefits to employees. Let your team know what’s available, how to sign up and how much they can contribute. Be sure to explain enrollment deadlines, reimbursement procedures and what happens to unused FSA funds.
  3. Set up payroll and administration. Decide whether to manage the plan yourself or bring in a third-party administrator. Make sure someone is responsible for payroll deductions, employee claims, tax reporting, plan updates and nondiscrimination testing.
  4. Keep an eye on compliance. Review employee eligibility and contributions throughout the year, check that payroll deductions match your administrator’s records and update your plan when tax rules or benefit limits change.

Getting the plan up and running is only the beginning. Truszkowski emphasized the importance of keeping your HR team informed as regulations change. “Once you have established your plan, create thorough policies and procedures to train HR staff and ensure that continuing education is happening, especially with the ever-evolving IRS regulations year to year,” Truszkowski added.

Section 125 nondiscrimination requirements

Once your Section 125 plan is in place, you’ll also need to make sure it meets IRS nondiscrimination requirements. Unless your plan qualifies for a safe harbor, such as the one available to simple cafeteria plans, you’ll generally need to pass three tests: 

  • Eligibility to participate: The plan can’t favor highly compensated individuals when determining which employees are eligible to participate.
  • Benefits and contributions: The benefits and contributions available through the plan can’t discriminate in favor of highly compensated participants.
  • Key employee concentration: No more than 25 percent of the plan’s total nontaxable benefits can go to key employees. Your administrator can help identify which employees fall into this category.

If your plan fails one of these tests, affected highly compensated participants or key employees may have to pay taxes on benefits that would otherwise be tax-free. That doesn’t mean every employee loses the tax benefit. Work with your administrator to review the results, address any problems and determine whether payroll corrections are needed.

Max Freedman and Mike Berner contributed to this article. Source interviews were conducted for a previous version of this article.

Did you find this content helpful?
Verified CheckThank you for your feedback!
MIranda Fraraccio
Written by: Miranda Fraraccio, Senior Writer
Miranda Fraraccio is a versatile small business expert who often shares her insights and guidance through the U.S. Chamber of Commerce. She leads small business owners and other business leaders to the resources necessary for their organizations to thrive, and breaks down important business concepts into actionable guides. At business.com, Fraraccio primarily covers a range of HR topics, including management theories, onboarding and benefits, employee development and more. Fraraccio, who studied communication at the University of Rhode Island, is also well-versed in other business areas, including funding, sales, marketing and social media management. She regularly spotlights businesses across the country that are making a difference in their communities.