Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
Learn what happens when an SBA loan goes into default, what your repayment and settlement options are and how to avoid further financial trouble.


Defaulting on a business loan can have serious consequences, including damage to your credit, the potential loss of personal or business assets and involvement from government agencies in the debt collection process. However, if you’re struggling to repay your U.S. Small Business Administration (SBA) loan, you may have options. Depending on your circumstances, you might be able to work out a repayment arrangement or negotiate a settlement through an offer in compromise. Below, we’ll explain what happens when an SBA loan goes into default and what you can do to protect your business and finances.
If you’re worried about missing an SBA loan payment, contact your lender as soon as possible. It’s also a good time to pull out your loan agreement and see what it says about missed payments and your options.
Searching for funding and not sure where to start? Tell us a little more about your business and get customized quotes from qualified providers.
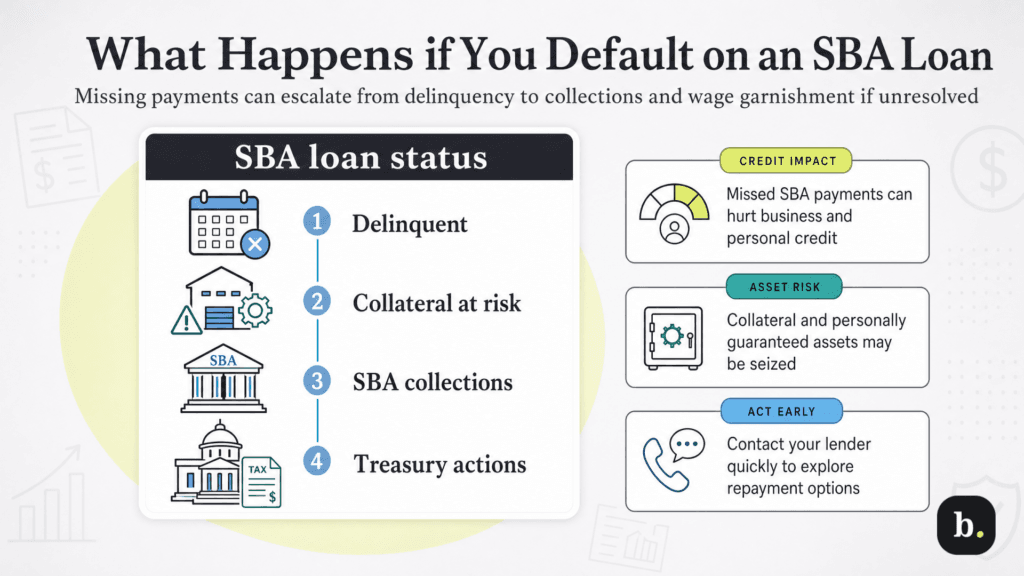
Defaulting on an SBA loan can have serious consequences for both your business and personal finances. The process depends on your loan type and circumstances, but here’s what you can generally expect:
Note that the steps above apply mainly to SBA loans made through banks and other lenders, including 7(a) loans. Disaster loans are different. If you have an Economic Injury Disaster Loan (EIDL), for example, you’ll work directly with the SBA rather than a bank.
The sooner you address missed payments, the more opportunities you may have to work with your lender or the SBA and avoid further financial trouble.
Defaulting on an SBA loan can damage your personal and business credit scores and potentially lead to asset seizures, wage garnishment or business lawsuits. These consequences aren’t automatic, but they’re important risks to understand.
Most SBA loans aren’t eligible for forgiveness, including loans issued through the agency’s popular 7(a) and 504 programs. However, the Paycheck Protection Program (PPP), established during the COVID-19 pandemic, allowed qualifying borrowers to have some or all of their loans forgiven.
The SBA’s PPP forgiveness guidelines gave borrowers five years to apply, starting from the date their SBA loan number was issued. With the program having ended in May 2021, those deadlines have generally come and gone. If you didn’t get your loan forgiven, you’re still responsible for paying back what you owe. If you’ve fallen behind on payments, your loan could be in default and your debt may be referred to the U.S. Treasury for collection.
Although forgiveness generally isn’t available for other SBA loans, borrowers struggling to make payments may qualify for other forms of relief. An SBA representative we spoke with recommended contacting your lender (or the SBA, if you have an EIDL) to discuss your options, which vary by loan type:
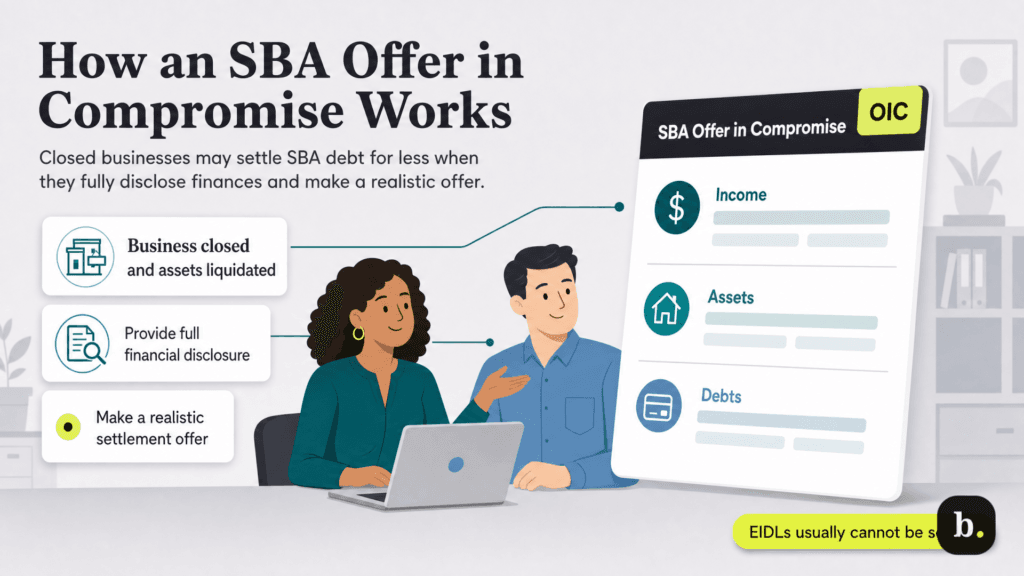
If your business has closed and you can’t repay your SBA loan in full, you may be eligible for a settlement through the SBA’s Offer in Compromise (OIC) process. An OIC allows qualifying borrowers and guarantors to settle their debt for less than the outstanding balance, generally after the collateral securing the loan has been liquidated.
The SBA considers several factors when reviewing an offer:
For 7(a) and 504 loans, contact your lender or Certified Development Company (CDC) about submitting an offer. Any settlement requires SBA approval. It’s best to explore this option before your debt is referred to the U.S. Treasury, since the collection process changes after referral.
If your offer is approved, you’ll need to fulfill the settlement terms before your debt is considered resolved. An OIC isn’t guaranteed, and the SBA may reject an offer if it determines that more money could reasonably be recovered.
COVID-19 Economic Injury Disaster Loans (EIDLs) are a different story. The SBA says these loans can’t be forgiven, and borrowers shouldn’t count on being able to settle for less than they owe. If you’re having trouble making payments on your COVID EIDL, your best bet is to contact the SBA directly and find out what options you have.
When applying for an offer in compromise, make sure you’re upfront about your finances. Don’t leave anything out, including 401(k) retirement plans or investment properties. Even if you think an asset can’t be used to repay your debt, you still need to disclose it if the SBA requires it. Leaving out information could put your settlement at risk.
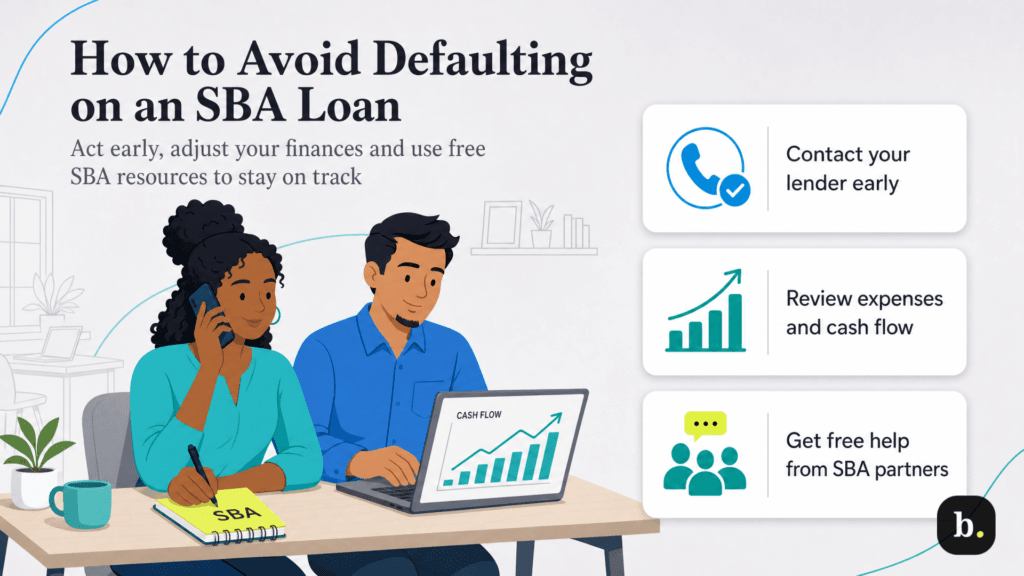
If you’re struggling to make your SBA loan payments, the best approach is to address the problem before your loan goes into default. The sooner you take action, the more options you may have.
Start by contacting your lender (or the SBA, if you have an EIDL loan) to explain your financial situation and ask about possible repayment arrangements or temporary payment relief. You should also take a close look at your business finances to see where you can make changes. Cutting business expenses, improving cash flow or restructuring other debt could help you free up money for your loan payments.
You don’t have to figure everything out on your own, either. The SBA works with organizations that provide free or low-cost business counseling and guidance, including:
You can find nearby organizations through the SBA’s local assistance page.
Financial difficulties can happen to any business, but ignoring missed payments can make the situation worse. Staying in touch with your lender or the SBA, reviewing your finances and seeking help early can give you a better chance of avoiding default and protecting your business’s credit and assets.