Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
Customers not paying? Here’s how to recoup your funds by charging interest and late fees on unpaid invoices.
Late payment charges — including late charge fees — are crucial tools for businesses to maintain cash flow. This article explains when and how to apply late fees, legal limits on maximum invoice late fees by state and best practices for enforcing policies effectively.
Searching for a collection agency and not sure where to start? Tell us a little more about your business and get customized quotes from qualified providers.
Late payment charges are financial penalties imposed on customers who fail to pay their invoices by the agreed-upon due date. These charges serve as both an incentive for timely payment and compensation for the inconvenience caused by delayed payments.
According to a PYMNTS Intelligence report, nearly 60 percent of invoices are paid late, with almost half outstanding for more than 90 days. This makes late payment charges an essential tool for businesses to maintain healthy cash flow.
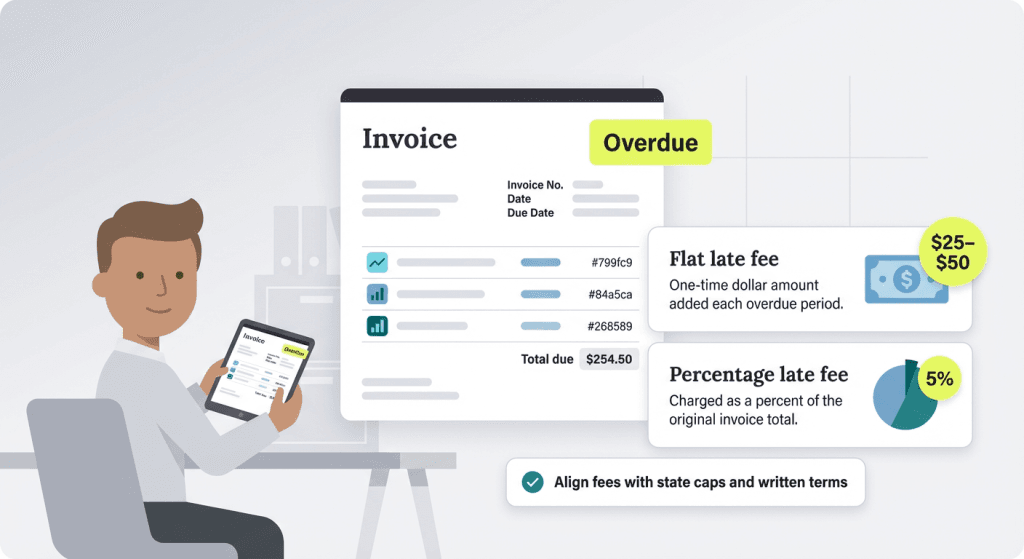
A late charge fee is a penalty amount you charge when a customer fails to pay by the invoice due date. Unlike interest fees that compound over time, these fees are added to the unpaid balance for each period payment remains overdue.
There are two main types of late payment charges:
Both types of charges must be clearly outlined in your written agreements and comply with state regulations to be legally enforceable.
“From my experience … I’ve seen that combining both [types of] fees works best for encouraging timely payments,” said Andrew Lokenauth, a fractional chief financial officer who is also the founder of Fluent In Finance and TheFinanceNewsletter.com.
You can assess multiple late fees as long as these terms were established in your written agreement before the sale, appear on your invoices and comply with state law. However, be mindful of state caps — if your state limits total penalties to 10 percent of the original invoice, interest fees might be more appropriate for larger balances.
The best accounting and invoicing software can help you effortlessly calculate and track interest and late fees on unpaid invoices. FreshBooks, in particular, has great tools for streamlining the payment process so you get paid what you’re owed.
Use this table to check allowable late payment charges by state. These represent general legal guidelines for business invoicing and are subject to change. Always verify current rules with a qualified attorney or your state’s legislative resources before enforcing late fees.
State | Max Late Fee | Grace Period | Notes |
|---|---|---|---|
Alabama | No maximum | None | |
Alaska | 5% above Federal Reserve or 10.5% per month | None | |
Arizona | No maximum | None | |
Arkansas | No maximum | None | |
California | No maximum | None | No statutory cap on invoice late fees |
Colorado | No maximum | None | |
Connecticut | No maximum | 9 days | |
Delaware | 5% per month | 5 days | |
Florida | No maximum | None | |
Georgia | No maximum | None | |
Hawaii | 8% per month | None | |
Idaho | 5% per month | 10 days | |
Illinois | No maximum | None | Must be reasonable |
Indiana | No maximum | None | |
Iowa | No maximum | None | |
Kansas | No maximum | None | |
Kentucky | No maximum | None | |
Louisiana | No maximum | None | |
Maine | 4% per month | 15 days | |
Maryland | 5% per month | None | |
Massachusetts | No maximum | 30 days | |
Michigan | No maximum | None | |
Minnesota | 8% per month | None | |
Mississippi | No maximum | None | |
Missouri | No maximum | None | |
Montana | No maximum | None | |
Nebraska | No maximum | None | |
Nevada | 5% per month | None | |
New Hampshire | No maximum | None | |
New Jersey | No maximum | None | |
New Mexico | 10% per month | None | |
New York | $50 or 5% per month, whichever is less | 5 days | More restrictive for consumer accounts |
North Carolina | $15 or 15% per month, whichever is greater | None | |
North Dakota | No maximum | None | |
Ohio | No maximum | None | |
Oklahoma | No maximum | None | |
Oregon | No maximum | None | Must be reasonable |
Pennsylvania | No maximum | None | |
Rhode Island | No maximum | None | |
South Carolina | No maximum | None | |
South Dakota | No maximum | None | |
Tennessee | $30 or 10% per month, whichever is greater | 5 days | |
Texas | No maximum | 2 days | Must be reasonable |
Utah | No maximum | None | |
Vermont | No maximum | None | |
Virginia | No maximum | 5 days | |
Washington | No maximum | None | |
West Virginia | No maximum | None | |
Wisconsin | No maximum | 5 days | |
Wyoming | No maximum | None | |
District of Columbia | No maximum | 5 days |
Note: This content is for informational purposes only and may not reflect the latest legal requirements. Consult a legal advisor for compliance in your state.
You charge the same dollar amount each time a payment is late. For example, on a $200 invoice with a $25 monthly late fee:
Some businesses calculate late fees as a percentage of the original invoice amount. Let’s say you have a 5 percent late fee policy and you invoice a client $1,000 with net 30 terms.
Month 1: The payment due date passes with no payment
Month 2: Customer still hasn’t paid
Month 3: Payment remains outstanding
With the percentage approach, the late fee stays at $50 each month because it’s always calculated from the original $1,000 invoice amount — not the growing balance. This is an important distinction from interest charges, which compound and increase over time.

Expect some clients to push back on late fees or interest charges — and be prepared to explain why they’re legitimate. Whether they hold up legally depends on whether you’ve followed the rules in your state.
“The legality of these fees is primarily governed by state laws, particularly those related to usury and contract law,” explained Ben Trigg, founder and CEO of Payello. “Usury laws set a limit on the interest rate that can be charged and contract law requires you to inform the customer about your fees.”
Before implementing any late fee or interest charge policy, ensure you complete these essential steps:
Send electronic invoices with a link to a secure online payment page. The immediacy and convenience can motivate disorganized clients and procrastinators to pay what you’re owed.
The key to charging interest or a late fee is to do it legally and without losing sight of your goals. Collecting the original invoice amount and maintaining a good relationship with the customer should always be your primary objectives. The experts we spoke with recommend following the best practices below.
Include your interest or late fee policy on all invoices as well as any statements and payment reminders. Our guide to creating a professional invoice details what else you should include.
There are other ways to collect on your unpaid invoices besides charging interest and late fees. You may want to consider the alternative options below.
Late fee charges are viable collection tactics that speed up the debt collection process and compensate you for the costs of interrupted cash flow and additional collection activity. As long as you do it correctly and don’t alienate customers or get in trouble with the law, you might find it preferable to the alternatives above.
“But most important of all,” Bird said, “is to set up a strong receivables process from the get-go, with … payment reminders before invoices become overdue in the first place.”
Late payment charges are additional fees imposed on customers who fail to pay their bills by the agreed-upon due date. These charges are typically added to the outstanding balance and serve two primary purposes: encouraging timely payments and compensating businesses for the inconvenience and additional costs caused by delayed payments.
Late payment charges are usually outlined in contracts or agreements and can take different forms — either as a fixed dollar amount (such as $25 to $50) or as a percentage of the overdue invoice amount (commonly 1 to 2 percent of the past-due balance).
Yes, you can legally charge late fees on invoices, but there are important requirements you must follow:
The legality of late fees is primarily governed by state laws, particularly those related to usury and contract law. Most experts recommend keeping fees at or below 10 percent annually to avoid legal issues.
Late fee limits vary significantly by state, and it’s important to check the rules that apply to your location before setting your policy. Here’s a general overview:
States with percentage caps:
States with hybrid limits:
States with no statutory maximum limits:
Some states also require grace periods before late fees can be applied. Always research your specific state’s laws or consult with a legal professional to ensure your policy is fully compliant.
Source interviews were conducted for a previous version of this article.