Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
Nonprofit accounting can be complex. This guide will help you understand your financial responsibilities and stay compliant.


If you run a nonprofit, your focus is likely on making a difference. But you also have donations to track, grants to manage and operating expenses to cover. Good accounting practices help you stay on top of your finances, meet reporting requirements and show donors how their support advances your mission.
Strong nonprofit accounting builds trust with donors and helps protect your organization’s financial health. Inaccurate records or missed filings can lead to penalties and, in some cases, the loss of tax-exempt status. This guide explains how nonprofit accounting works, highlights common accounting challenges nonprofits face and outlines how to stay compliant.
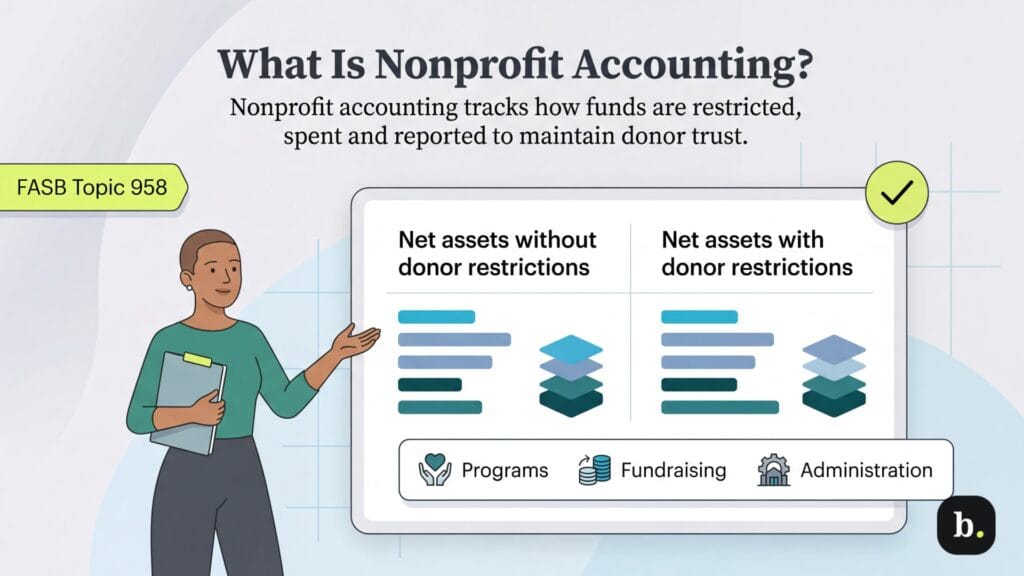
Nonprofit accounting is a system of financial management, recordkeeping and reporting designed for nonprofit organizations. Unlike for-profit businesses, nonprofits operate to fulfill a mission rather than generate profits for owners or shareholders. They may also qualify for federal income tax exemption under Section 501(c)(3) or another provision of the Internal Revenue Code. However, forming a nonprofit under state law doesn’t automatically make an organization tax-exempt.
Nonprofits that prepare financial statements under generally accepted accounting principles (GAAP) follow nonprofit-specific standards established by the Financial Accounting Standards Board (FASB), including Topic 958, Not-for-Profit Entities.
One important difference in nonprofit accounting is how organizations classify their net assets. Under FASB’s financial reporting standards, nongovernmental nonprofits that follow GAAP use two categories:
Here are a few other key terms and concepts you’ll encounter in nonprofit accounting:
Nonprofits following GAAP must also report expenses by both function (such as programs and fundraising) and type, also called natural classification (such as salaries and rent). Expense allocations should reflect how resources are actually used, not be adjusted to make administrative costs appear smaller. While donors may pay attention to overhead costs, which generally include administration and fundraising expenses, low overhead doesn’t necessarily mean a nonprofit is more effective. Spending on staff, technology and other operational needs is often essential to delivering quality programs.
Build budget planning into your regular operations. Create an annual budget and a three- to five-year plan for major initiatives, then revisit both throughout the year to compare actual revenue and expenses against your projections.
Nonprofits rely on good bookkeeping and accounting to manage their finances and stay compliant. The terms are often used interchangeably, but there’s a difference between the two.
Nonprofit and traditional business accounting follow many of the same principles, but there are some important differences in how organizations handle revenue, expenses and financial reporting. Nonprofits must account for donations, grants and donor restrictions, while for-profit businesses typically focus on sales, expenses and profitability. Here’s how they compare:
Aspect | Nonprofit | For-profit |
|---|---|---|
Primary organizational focus | Fulfilling the organization’s mission and managing resources responsibly | Generating profits and building business value |
Net assets and equity | Net assets with and without donor restrictions | Owners’ or shareholders’ equity, including retained earnings where applicable |
Revenue recognition | Distinguishes contributions from exchange transactions, such as sales and services | Primarily recognizes revenue from sales and services |
Expense reporting | Classifies expenses by function (programs, management and general, fundraising) and type (salaries, rent, etc.) | Reports expenses using categories such as cost of goods sold and operating expenses |
Tax status | May qualify for federal income tax exemption; unrelated business income may still be taxable | Business income is generally taxable to the entity or its owners, depending on tax classification |
Financial statements | Statements of financial position, activities and cash flows, plus an analysis of expenses by function and type | Balance sheet, income statement, statement of cash flows and statement of changes in equity |
One of the biggest practical differences is how nonprofits handle money designated for a particular purpose. For example, if a donor gives $10,000 to fund a scholarship program, the nonprofit must track that restriction and account for the money accordingly. A business receiving $10,000 in ordinary sales revenue generally doesn’t face the same donor-imposed restrictions.
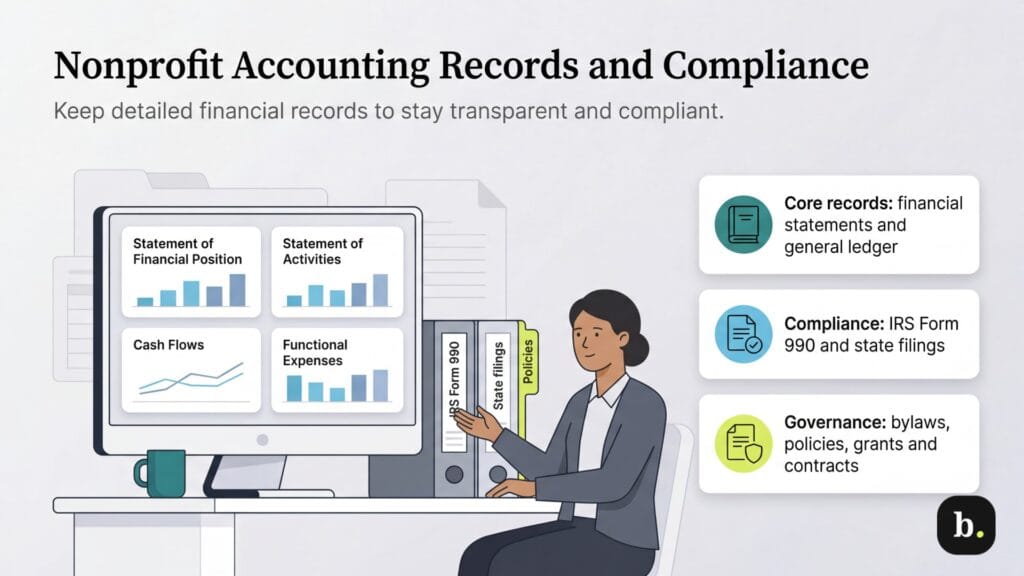
Nonprofits must maintain detailed financial records and meet strict reporting requirements at both the federal and state levels. Together, these responsibilities ensure transparency, support decision-making and help organizations stay compliant.
Here’s a closer look at the key records nonprofits must maintain and the compliance requirements they need to meet.
Nonprofit accounting relies on accurate, well-organized records that show how funds are received, managed and spent. These documents support financial reporting, demonstrate accountability to donors and help ensure compliance with regulatory requirements. Key records include the following:
Financial statements:
Supporting financial documentation:
Organizational and compliance records:
Nonprofits must also comply with federal tax regulations that govern how they report financial activity and maintain their tax-exempt status.
IRS Form 990 filing requirements and deadlines
Form 990 gives the IRS and the public a detailed look at a nonprofit’s finances, activities and operations. Most tax-exempt organizations must file an annual return or notice, although the required form depends on the organization’s size and type. Churches and certain other organizations are generally exempt from annual filing requirements.
The IRS filing thresholds generally work as follows:
These are general thresholds, and exceptions apply depending on the organization.
What Form 990 reports
Form 990 provides information about an organization’s finances, management and activities. Depending on the organization and applicable reporting requirements, it may include:
Filing deadlines and extensions
Form 990-series returns and Form 990-N are generally due on the 15th day of the fifth month after the organization’s tax year ends. For nonprofits operating on a calendar year, that’s May 15. If the deadline falls on a weekend or legal holiday, it moves to the next business day.
Organizations filing Form 990, 990-EZ or 990-PF can request an automatic six-month extension by submitting Form 8868 by the original filing deadline. However, Form 990-N filers can’t request an extension, and an extension to file doesn’t extend the deadline for paying any taxes owed.
Organizations required to file an annual return or notice generally lose their tax-exempt status automatically if they fail to file for three consecutive years. This includes organizations required to file Form 990-N.
Unrelated business taxable income (UBTI)
Tax exemption doesn’t cover every source of income. According to the IRS, income from a business activity that is regularly carried on and isn’t substantially related to the nonprofit’s tax-exempt purpose may be taxable. Certain exceptions and exclusions apply. And even if the proceeds support your mission, that alone doesn’t make the activity tax-exempt.
For example, if a nonprofit regularly operates a business unrelated to its mission, the income may be taxable even if all the profits go toward its programs.
Organizations with $1,000 or more in gross income from an unrelated business generally must file Form 990-T in addition to their annual information return, if required. Nonprofits with multiple unrelated businesses generally must calculate taxable income separately for each activity rather than use losses from one to offset income from another. Keep separate records for these activities and consult a nonprofit tax professional if you’re unsure how the income should be classified.
In addition to federal obligations, nonprofits must follow state laws governing registration, fundraising and financial reporting. Requirements vary considerably, and an organization may have obligations in more than one state.
According to the National Council of Nonprofits, most states require nonprofits to register before asking residents for donations. You may also have additional registration or reporting obligations in states where your nonprofit holds charitable assets, runs programs or has a business presence.
There isn’t a single registration threshold or filing deadline that applies nationwide. States have different revenue thresholds, exemptions and rules for online fundraising. You’ll need to check the requirements in each state where your nonprofit operates or raises money, including whether you must register as a charitable solicitor, maintain a corporate registration or apply separately for state tax exemption.
Annual reporting requirements also vary. For example, California’s attorney general generally requires registered charities to renew their registration four months and 15 days after the fiscal year ends. That’s May 15 for organizations using a calendar year, although extensions may apply. New York and Minnesota have their own filing instructions and deadlines.
Some states accept a copy of IRS Form 990 as part of their annual reporting requirements, but additional state forms, fees or filings may still be necessary.
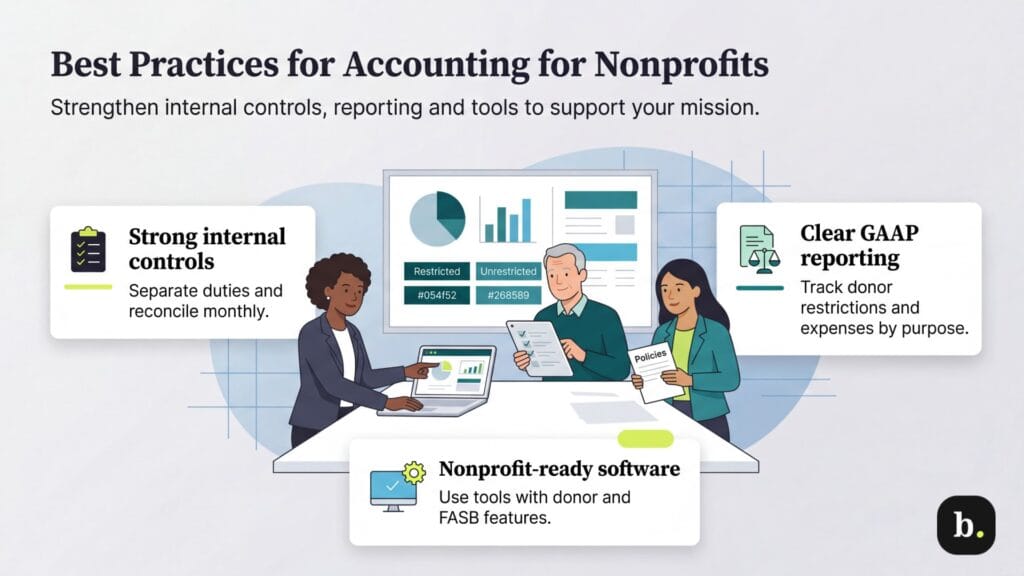
Nonprofit organizations must balance mission-driven work with responsible financial tracking and management. Here are some best practices nonprofits should follow:
Good internal controls can help your nonprofit avoid costly accounting mistakes and protect against fraud. Here are a few practices worth putting in place:
Make sure employees and volunteers know your organization’s financial policies and understand their responsibilities. Review these procedures regularly to help prevent accounting mistakes and employee fraud.
GAAP provides a consistent framework for preparing financial statements. Not every nonprofit is required to prepare GAAP financial statements, but grant agreements, lenders or state laws may require them.
If your nonprofit follows GAAP, pay particular attention to these areas:
No matter who manages your books, choosing the right accounting software can make it much easier to track your nonprofit’s finances and prepare financial reports. Look for features such as fund and grant tracking, reporting by program, approval controls and integration with your donor management system. Just remember that even the best software needs to be set up correctly and backed by sound accounting practices.
Several accounting platforms are designed specifically for nonprofits, including:
You can also use one of the more traditional best accounting software platforms to manage nonprofit finances. Some options include:
Before making a decision, compare the software’s nonprofit-specific features, plan restrictions, integration options and total costs, including any implementation or training expenses.
No matter which software you use, communication is an important part of managing your nonprofit’s finances. Tiffany Couch, a CPA and CEO of forensic accounting firm Acuity Forensics, recommends keeping staff and board members informed about the organization’s financial health and any issues the accounting team uncovers.
“Make sure you have a CPA who will walk you through your numbers — ensuring that you understand the profit-and-loss statement, the balance sheet and your cash flow statement,” Couch advised. “The more knowledgeable you become, the more empowered you are to make financial decisions that support your organization.”
Couch emphasized that regular communication between accountants and decision-makers helps nonprofits make informed choices and plan for the future. “If you don’t have a CPA assisting you in this process, find one who will.”
Here are a few examples of how nonprofits handle different types of contributions:
Keep in mind that GAAP and IRS reporting rules aren’t always the same. For example, even if you recognize donated services or the free use of facilities in your financial statements, the IRS Form 990 instructions say not to include their value as revenue or expenses in Parts VIII and IX. You can still describe these contributions in the section about your nonprofit’s programs. Your accountant can help make sure they’re reported correctly.
Nonprofits need reliable financial oversight, but not every organization can afford a full-time accountant or dedicated accounting and finance team. As a result, bookkeeping and other financial responsibilities sometimes fall to staff members or volunteers who don’t have accounting experience. That can lead to costly mistakes, according to Couch.
These mistakes aren’t necessarily intentional. Someone unfamiliar with nonprofit accounting may overlook donor restrictions, misclassify expenses or miss important filing deadlines. And when a volunteer or staff member leaves, the organization may struggle to pick up where they left off if records and procedures aren’t well documented. Even if you can’t hire an accountant full-time, it’s worth getting professional guidance when you need it.
“Don’t have a mindset of scarcity when it comes to ensuring you have appropriate resources in terms of handling your money,” Couch advised. “There are plenty of CPAs who would be willing to provide a discount or pro bono services.”
Hiring a CPA can help your nonprofit navigate tax requirements, prepare financial statements and keep up with required filings.
At its core, nonprofit accounting comes down to accountability. Nonprofits answer to a broad mix of stakeholders, all with their own expectations. That group usually includes:
That’s why getting your accounting right matters. Clear financial records show how funds are used, help maintain donors’ trust and give supporters confidence that their contributions are making a difference.
Mike Berner contributed to this article. Source interviews were conducted for a previous version of this article.