Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
When you need a loan for your business, potential lenders may ask to see your audited financial statement. Learn what this is and why lenders want to see it before they approve your business loan.

When you apply for business funding, lenders and investors want to ensure they won’t lose money on your venture. That’s why bringing detailed financial statements to your pitch meeting is crucial.
However, if potential stakeholders still have concerns about your company’s finances, it may be because you haven’t prepared an audited financial statement. Below, we’ll explain what an audited financial statement is and how it differs from an unaudited financial statement.
An audited financial statement is an independent, objective evaluation of a company’s financial records by a certified public accountant (CPA). When a CPA firm audits financial statements, it ensures the business adheres to Generally Accepted Accounting Principles (GAAP) and professional auditing standards. The audit process provides the highest level of assurance that financial statements accurately reflect a company’s financial position and performance.
Without CPA verification, investors and lenders may question the accuracy of your financial reports. Such trepidation can reduce their confidence in your company’s financial stability.
An audited financial statement includes a detailed examination of these four key financial reports:
Darian Shimy recommended stringent preparation for this process, including using one of the best accounting software platforms to streamline recordkeeping. “I also suggest engaging a qualified CPA or auditing firm early in the process, as their guidance can prevent issues and simplify the audit,” Shimy, CEO and founder of FutureFund, added.
An audited financial statement also includes an opinion letter from the CPA who assessed your reliability.
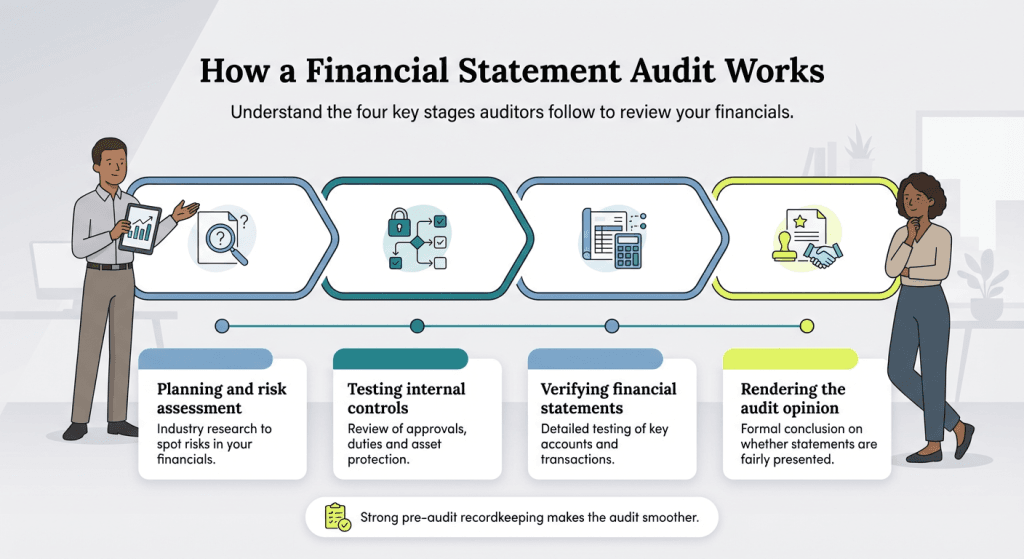
An audit of financial statements typically follows four key stages: planning and risk assessment, internal control testing, thorough statement verification and rendering an opinion.
Pristine and careful pre-audit recordkeeping will help you avoid small business accounting mistakes and smooth the audit process.
Auditors provide different opinions based on their evaluation of an organization’s financial statements, each reflecting varying levels of confidence in the accuracy and fairness of the presented information.
An unqualified opinion, also called a clean opinion, represents the best outcome for any organization. The auditor concludes that financial statements present a true and fair view of the company’s financial position in accordance with applicable accounting standards. This opinion indicates no material misstatements were found, and the company has maintained proper accounting records and followed appropriate procedures throughout the reporting period.
A qualified opinion arises when auditors discover specific issues that are material but not pervasive enough to invalidate the entire financial statement. This opinion typically includes an “except for” clause highlighting particular areas of concern. Common reasons include limitations in audit scope, minor departures from accounting standards or insufficient evidence for certain transactions. While less favorable than an unqualified opinion, it suggests most financial information remains reliable.
Adverse opinion
An adverse opinion represents a serious red flag for stakeholders. Auditors issue this opinion when they determine that financial statements contain material misstatements that are both significant and pervasive, fundamentally misrepresenting the organization’s financial health. This opinion indicates widespread problems with accounting practices, suggesting the statements cannot be relied upon for decision-making purposes. Companies receiving adverse opinions often face severe consequences, including loss of investor confidence and potential regulatory action.
A disclaimer occurs when auditors cannot form an opinion due to insufficient evidence or significant scope limitations preventing them from completing their examination. Unlike an adverse opinion, this doesn’t necessarily indicate problems exist. Rather, the auditor simply lacks adequate information to make a determination. Common causes include management restrictions on audit procedures or incomplete records.
Do you expect to receive funding from one of the best business loan and financing options? Then you’ll want to obtain an unqualified opinion from your CPA before applying for financing. “Unqualified” in an audit opinion basically means “all clear.”
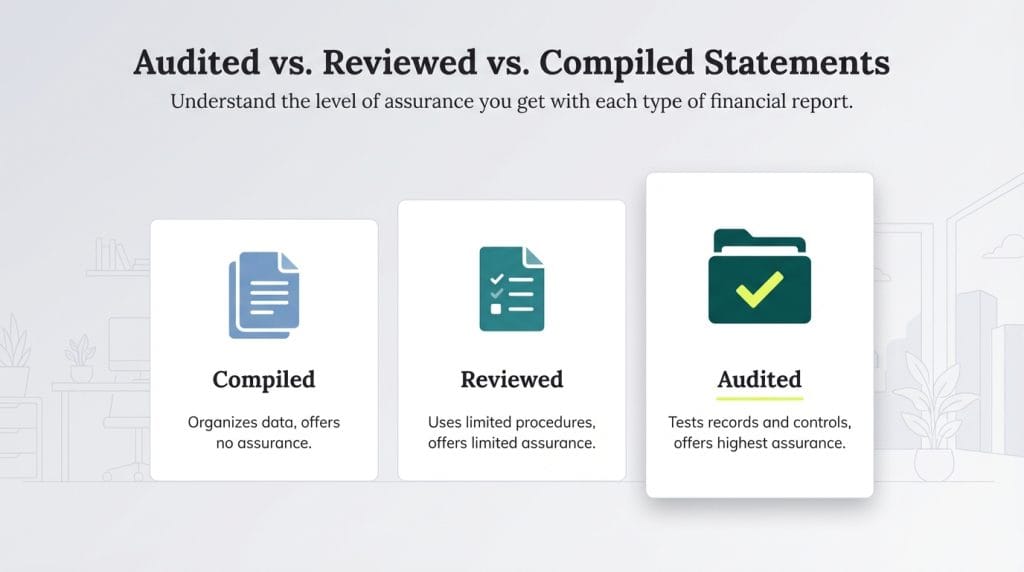
Audited reports differ from other formal accounting reports, such as compiled reports and reviewed reports. These three types of financial statement services vary significantly in their level of assurance, complexity, cost and appropriate use cases.
The primary differences between audited and unaudited financial statements are a CPA’s involvement and an in-depth verification process. However, hiring the right accountant — whether or not they are a CPA — is key to ensuring accurate, reliable financial reporting.
Audited financial statements are particularly valuable when applying for a business loan or seeking investor funding. These stakeholders want to ensure they are making a sound financial decision. The type of audit opinion can significantly impact a company’s access to capital, as lenders and investors often rely on audit reports to assess the company’s financial health and risk profile.
Shimy, whose platform helps K-12 schools streamline fundraising and volunteering, emphasized that growing businesses may find value in audited financial statements. “At FutureFund, having clear, audited financials has been key to earning the trust of school districts and demonstrating accountability,” Shimy explained.
Beyond securing financing, a clean audit opinion can enhance the company’s reputation and boost investor confidence, while a qualified, adverse or disclaimer of opinion can raise red flags about the company’s financial health and governance. Audited financials also demonstrate transparency and accountability, which are essential for building trust with regulators and other external stakeholders.
Having a CPA audit your business’s financials can help you catch or prevent employee accounting fraud.
Crystal Stranger, CEO of OpticTax.com, noted that most businesses do not need audited financial statements, especially since audits can cost thousands of dollars. Typically, only companies publicly financed and regulated by the SEC are required to have audited financials.
“However, in certain situations, a set of audited financials can be helpful, such as when seeking a bank loan, during a partnership dissolution, or when executing equity exchanges from financial instruments such as options or SAFE notes,” Stranger explained.
Common scenarios requiring or benefiting from audited financial statements include:
Type | Assurance Level | Preparation Level | Ideal For |
|---|---|---|---|
Compiled | None | CPA assembles statements from records | Internal management reviews, very small firms |
Reviewed | Limited | CPA inquiry and analytics only | Small businesses seeking financing, partnership agreements |
Audited | High | CPA conducts full audit, opinion issued | Public firms, SEC compliance, major financing, investor requirements, contracts |
Most small businesses do not need audited financial statements unless required by lenders, investors or regulatory bodies. Audits are expensive and primarily necessary for publicly traded companies regulated by the SEC. However, small businesses may choose to obtain audited financials voluntarily when seeking bank loans, major investment rounds or during partnership changes to build credibility with stakeholders.
Audited financial statements often take weeks or even months to complete, depending on the size and complexity of the business. The timeline varies based on factors such as the company’s preparedness, the strength of internal controls, transaction volume and industry-specific requirements. Companies with well-organized financial records and strong internal controls typically experience shorter audit timelines.
A financial audit generally costs between $7,000 and $50,000 or more. However, this will depend on key factors such as your company size, industry, revenue, operation complexities and internal controls.
An audit is a formal, structured examination of financial statements conducted by an independent CPA to provide assurance that the statements are accurate and comply with GAAP. Due diligence, on the other hand, is a broader investigative process typically conducted before mergers, acquisitions or major investments. While due diligence may include reviewing audited financial statements, it also examines legal compliance, operational efficiency, market position, intellectual property and potential risks beyond financial reporting. Audits follow standardized procedures defined by professional auditing standards, whereas due diligence processes are customized to each transaction’s specific needs.
Max Freedman contributed to this article. Source interviews were conducted for a previous version.