Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
While indemnity insurance isn't a specific policy type, it does play a critical role in the types of insurance your business needs.

From property to general liability, choosing business insurance takes careful thought and consideration. While they all serve different purposes, one key attribute all policies have in common is that they protect the insured business from having to pay the full cost of incurred losses. This is referred to as “indemnity insurance.”
Most business insurance is a form of indemnity insurance because it’s designed to make another party whole for losses incurred during the policy term. We’ll explain what indemnity insurance is, who needs it, what it covers and how much it typically costs.
Indemnity insurance is a contractual agreement between a policyholder and an insurance carrier stating that, in exchange for a premium, the insurance company will cover financial losses resulting from a covered claim.
“[It] helps businesses defend their legal claims, losses or damages by providing financial coverage of a business’s liabilities, usually in cases such as professional negligence or breach of contract,” explained Dennis Shirshikov, Adjunct Professor of Economics at City University of New York.
To indemnify someone means to compensate them for any harm or loss they may incur. In insurance, indemnity can also mean protection from legal liability related to operations or actions. An indemnity insurance policy, therefore, covers damages that result from a covered loss.

While most insurance policies are considered a form of indemnity agreement, only certain professions are required to carry indemnity insurance, often in the form of malpractice insurance or errors and omissions (E&O) insurance.
“Indemnity insurance is commonly needed by businesses in professional services, consultancy, technology, healthcare and construction, particularly those exposed to high financial liabilities arising from errors and omissions in their operations,” Shirshikov explained.
In other words, this type of insurance is designed for professional service providers who may incur financial losses or harm to their clients due to errors or omissions in their work.
Here are some common professions that are required to carry indemnity insurance:
While these professionals are required to carry professional liability insurance to maintain their licenses, most businesses can also benefit from indemnity insurance, whether for professional services, general liability or commercial property protection.
For example, say a shoe store experiences a fire in its storage room. It loses $15,000 worth of inventory, and the leased building suffers $50,000 in damage. The store owner has a commercial property insurance policy and is indemnified for the losses, meaning the building owner receives funds for repairs, and the store owner is reimbursed for the lost inventory.
Builder’s risk insurance is a type of indemnity insurance for property owners, general contractors, subcontractors, building leads and architects. It protects against losses and damages that occur during new construction, remodeling or installation projects.
Indemnity insurance protects against financial losses in several ways. Depending on the policy and the type of claim, it may:
“If a client claims your service or advice caused them harm, this policy helps cover legal fees, settlements and judgments,” explained Chris Peterie, the chief executive officer of Tower Street Insurance.
Different types of insurance indemnify different types of losses. For example:
Your policy type determines what’s covered and what’s excluded. Most indemnity policies do not cover intentional damage or illegal activity.
When a loss occurs, the policyholder contacts their provider to file an insurance claim. The provider assigns a claims representative to assess the damage and coordinate any payouts according to the contract terms. If a third party is involved, payments may be made directly to them rather than to the policyholder.
If you can’t operate your business due to a fire, wind damage, theft, falling objects, damaging cyberattacks or lightning, business interruption insurance can help cover ongoing costs, including payroll and taxes, until you’re back up and running.
An indemnity policy can cover many types of losses, depending on the type of insurance. As long as the loss falls within the policy’s terms, the insurance carrier will pay for it.
Slip-and-fall accidents | Covered under a general liability insurance policy, these claims typically pay for the injured party’s medical expenses and lost income. |
|---|---|
Medical mishaps | A medical malpractice insurance policy covers damages a patient may incur if a healthcare provider makes a mistake. |
Property theft | Commercial property insurance reimburses the business for stolen property, such as computers or inventory (minus any applicable deductible). |
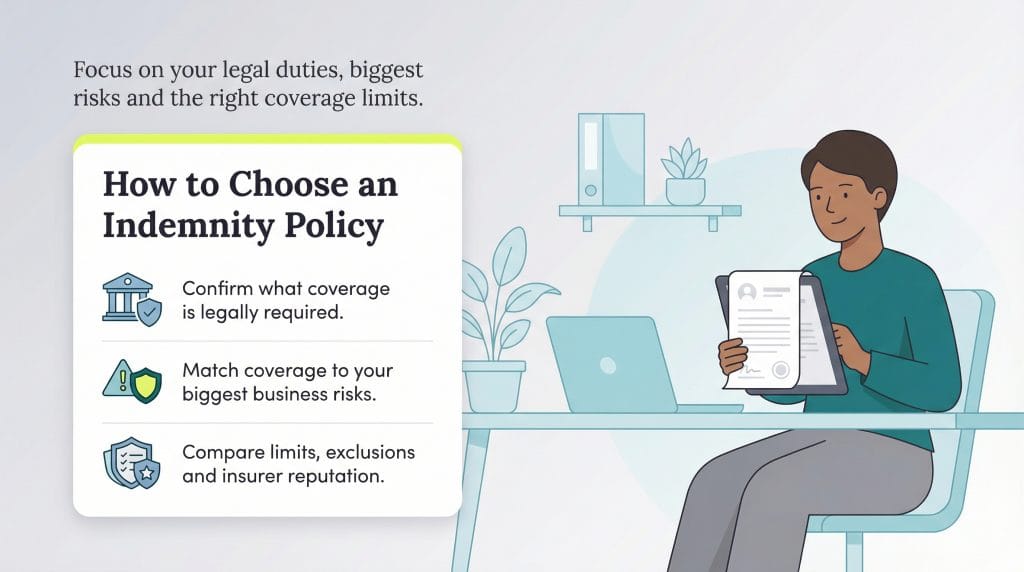
Finding the right indemnity policy doesn’t have to be overwhelming. Use these tips to narrow your options and choose coverage that makes sense for your business.
If your business faces unique risks that standard policies don’t cover, you may need specialty insurance, which can include tailored indemnity protection to safeguard against specific liabilities.
The cost of indemnity insurance will depend on the type of policy you choose and your business’s industry, revenue, location and other factors. A general liability insurance policy could cost as little as $500 per year, while professional liability insurance tends to be more expensive, depending on your profession. On average, companies spend $500 to $1,000 annually per employee on E&O insurance. Property insurance costs vary based on the value of the property being insured.
It’s best to discuss your coverage needs with an insurance agent to ensure you’re getting the right protection for your biggest risks. Be sure to compare quotes from multiple providers and ask about available discounts to save money on business insurance and secure the best possible rate.
As with all types of insurance, there are upsides and downsides to indemnity coverage. Here are some advantages and disadvantages to consider.
While you typically can’t choose your own legal team under an indemnity policy, insurers assign experienced defense attorneys to represent you in the event of a false or malicious claim.
While most insurance is based on the principle of indemnity, not every policy qualifies as an indemnity insurance policy. Life insurance is a common exception because the loss (a life) isn’t financially measurable; the payout is a pre-agreed sum rather than one based on the actual value of the loss.
For a policy to be considered indemnity insurance, the payment must be closely tied to the replacement cost, fair market value or reimbursable expenses. In other words, the payout must directly reflect the actual loss experienced by the policyholder or a third party.
Commercial indemnity insurance policies themselves aren’t transferable. However, as the policyholder, you can transfer the benefit of indemnity to third parties who suffer a covered loss resulting from your business. These third parties don’t own the policy or pay for it, but they’re still protected through your contractual agreement with the insurance carrier.
There are also cases where you may want to transfer risk to someone else. For example, if you hire a contractor, you might require them to indemnify you from their own business risks. This is often done by having them name you as an additional insured on their policy, which offers you protection while they work on your behalf. In this case, you’re transferring risk, not the actual policy.
Indemnity insurance covers business owners, contractors, freelancers and other professionals against third-party claims for losses or damages. If a claim is successful, and you’re found liable for the loss, your insurance will cover the awarded compensation, as well as legal fees and related costs, up to your policy’s limit. Without coverage, you’d be responsible for paying these expenses out of pocket.
Professional indemnity policies generally exclude:
Kimberlee Leonard contributed to this article.