Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
Borrowing the right amount can help your business grow, but taking on too much debt can lead to financial instability.

Starting a small business can take a lot of time and money, which is why many entrepreneurs leverage debt in the beginning. Businesses can use borrowed funds to manage cash flow, make supplier payments and invest in growth opportunities. In this way, debt can be a useful tool to get your business off the ground, but you must make sure it works for you, not against you.
This guide will help you understand how much you should borrow for your business and what level of business debt can be responsibly managed.
How much money you can borrow starts with the types of loans a lender offers and its limits for each product. Some government-backed programs have published maximums, while conventional and online loan amounts depend on the lender, your qualifications and the purpose of the financing.
Loan type | Amount or limit | What to know |
|---|---|---|
SBA 7(a) | $5 million maximum | General-purpose business financing, subject to program eligibility. |
SBA 504 | Up to $5.5 million | SBA-backed portion for eligible fixed-asset projects; total project financing can be larger. |
SBA Express | $500,000 maximum | A delivery method within the 7(a) program. |
Bank term loan | Varies by lender | Amount depends on repayment capacity, collateral and underwriting. |
Online lender | Varies by provider and product | Online lender describes a lending channel, not a single loan type. |
Business line of credit | Varies by lender | A revolving limit; interest generally applies to amounts drawn. |
Equipment financing | Varies by lender and asset | The asset value and any down payment affect the amount financed. |
SBA microloan | $50,000 maximum | Available through SBA-approved intermediary lenders. |
However, just because the maximum term loan a lender offers is $3 million, for example, doesn’t mean you’ll qualify to borrow that much. How much a lender will actually offer you depends on your business’s circumstances, including factors like your credit score, average monthly revenue, cash flow and reserves.
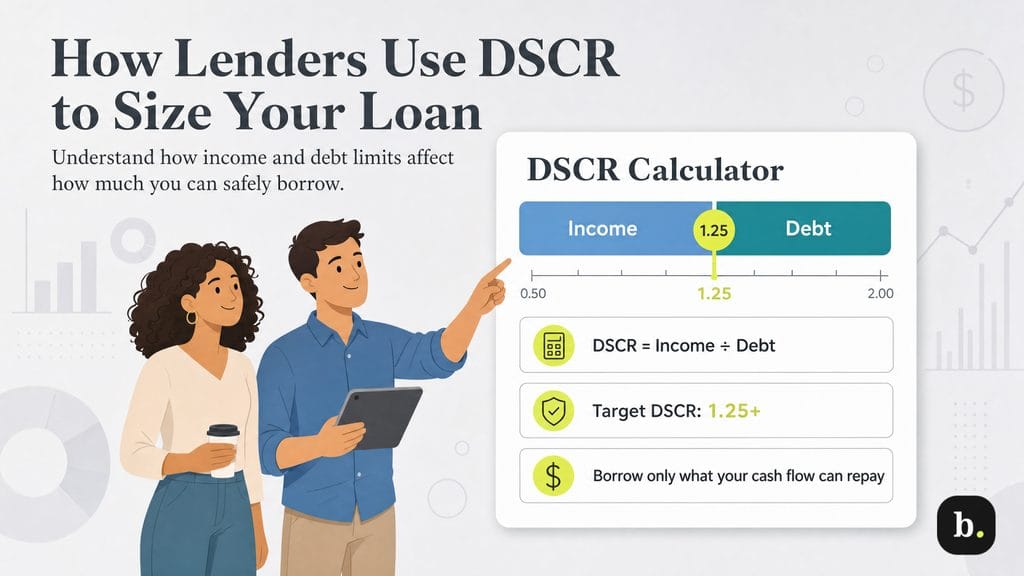
Lenders often use the debt service coverage ratio (DSCR) to evaluate repayment capacity. Banks commonly look for a DSCR of at least 1.25, but requirements vary by lender, loan program and industry. A common calculation is:
DSCR = Net operating income / Total annual debt service
For example, if a business generates $150,000 in annual net operating income and its existing debt payments total $80,000 per year, its DSCR is 1.875, which is above the 1.25 threshold most lenders require. A lender would then calculate the maximum additional debt payment you could sustain while maintaining a 1.25 DSCR or greater. In this case, the business would be able to manage up to $120,000 in total debt payments annually, or an additional $40,000 in annual debt service payments, while maintaining a 1.25 DSCR.
Even if you do qualify for the maximum amount a lender offers, it doesn’t necessarily mean you should take it. A good rule is to borrow the least amount required to achieve a specific purpose, and always with a clear repayment plan supported by existing revenue and cash reserves.
Total business debt should not exceed more than three times your EBITDA (earnings before interest, taxes, depreciation and amortization). That means if your EBITDA is $100,000 per year, you shouldn’t carry more than $300,000 in total debt.
Total debt doesn’t paint the whole picture, though — you need to consider your debt service, or the repayment amounts due on your total debt each month. Your debt-to-income ratio should not exceed 36 percent. For example, if your business has an average gross monthly revenue of $10,000, you should be spending no more than $3,600 on debt service.
Of course, there are exceptions to this rule. You may consider exceeding this limit if you believe you have a clear opportunity to grow revenue and need investment capital to do it. However, it is important to always have a clear repayment plan that’s grounded in existing revenue; avoid factoring in expected future revenue into your debt service budget in case it doesn’t materialize.
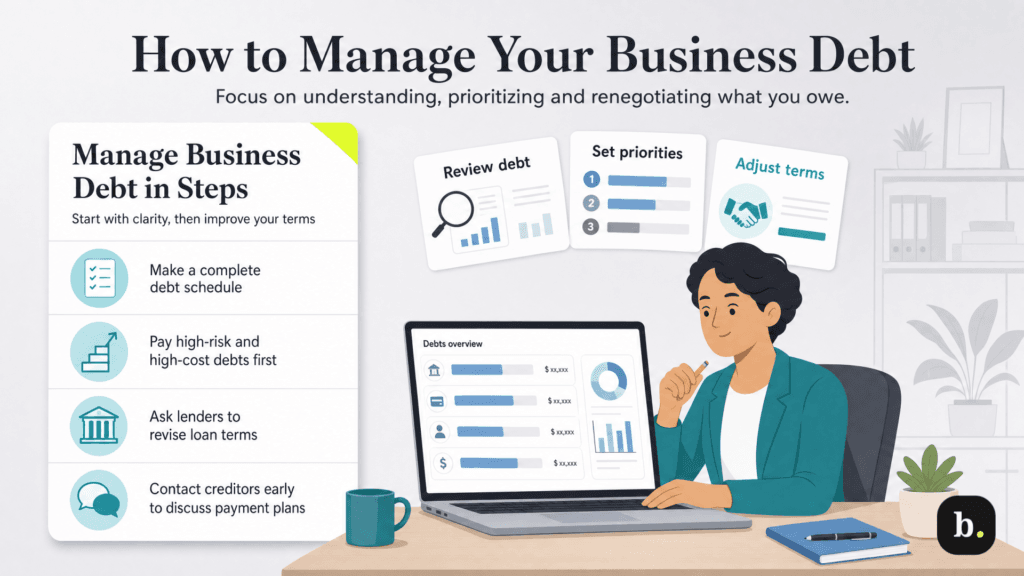
If your business debt no longer benefits your company and is starting to hurt you, here are four steps you can take to manage it.
Start with a complete debt schedule, whether you maintain it in a spreadsheet or accounting software. List each creditor, outstanding balance, interest rate, required payment, due date and maturity date. Include any collateral, personal guarantees, balloon payments and prepayment charges so you can identify the most urgent risks.
Consider using small business accounting software, which allows you to get a complete picture of your company’s assets and liabilities. These platforms can automate expense categories, helping you identify where your money is going. This will help you develop a workable plan for paying down your debt.
Learn more about accounting software in our Xero Review
Not all debt is equal and some types are more problematic than others. For instance, high-interest credit card debt should be dealt with before paying off a small business loan with a low interest rate.
Ask yourself what would happen if you didn’t pay a particular debt right away and make decisions about prioritizing your debts based on the seriousness of the consequences. The more unpleasant the result, the higher priority paying off the debt should be.
Most often, meeting payroll obligations takes priority since you need to pay your employees to retain them and continue running your business. Before making payments to suppliers, vendors and creditors, focus on clearing your payroll liabilities.
One option for managing debt related to business loans is to approach your bank (or other loan provider) and attempt to renegotiate your loan repayment terms and conditions. If you’re a long-time customer, the lender may be willing to work with you to lower your interest rate or monthly payments. Even if an interest rate reduction isn’t possible, lenders might agree to extend the loan term to lower your monthly payment. A longer repayment term may increase the total interest you pay, even if it reduces your monthly bill. Get revised terms in writing and review any fees or changes to collateral and guarantees.
If you’re having trouble paying your monthly loan installments or other debts, speak to your creditors before missing a payment. Explain the cash shortfall, and suggest a realistic payment plan. A creditor may work with you, but approval is not guaranteed. Confirm in writing how interest, fees, credit reporting and the repayment schedule will be handled.
>>FREE TOOL:: Debt Payoff Calculator
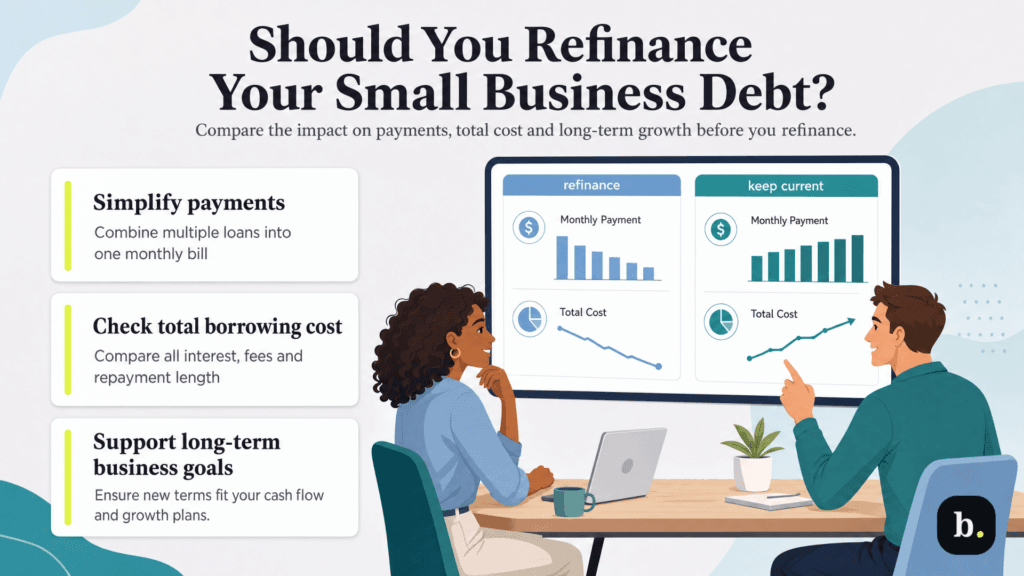
Refinancing replaces an existing debt with new financing. Business debt consolidation combines multiple debts into one new obligation and can be a form of refinancing. Either may help if the new terms fit your cash flow and goals; neither automatically lowers your borrowing costs.
If you’re tired of juggling multiple due dates, bills and interest rates, refinancing can make your life easier. Refinancing will provide you with a single loan, so you’ll have one debt payment to keep track of instead of several
“If your business is making multiple monthly payments on business credit cards, equipment financing and working capital loans, your life as a business owner could be simplified by consolidating those into one financing option and one debt payment,” said Ben Johnston, chief operating officer of Kapitus.
Saving money is one reason to refinance. If your credit profile or business finances have improved since you took out the original loan, you might qualify for better terms. Compare the remaining cost of your current debt with all payments and fees under the new offer, including origination fees, closing costs and any prepayment charge on the old loan. A lower monthly payment does not necessarily mean a lower total cost.
Johnston cited high interest rates as a top reason to consolidate your debts into a more affordable business line of credit or loan. However, there may be strings attached. “You may be required to offer a personal guarantee or some other form of collateral,” he told us.
You may be able to increase cash flow by refinancing short-term debt into a longer-term loan with smaller required payments. That can leave more cash available for operations, but it may also mean paying interest for longer. Make sure the new payment remains affordable in slower months.
Combining your debt into a single payment could improve your business credit score. Whenever you refinance a commercial loan, you might see a sudden jump in your credit score since it reduces your credit utilization ratio.
Debt comes with many negative connotations, but as mentioned above, business debt isn’t always a bad thing. When used responsibly, it can help your business in the long run. Here are a few reasons why debt can be good for businesses:
Here are a few reasons you may not want to take on business debt:
Mike Berner contributed to the reporting and writing in this article. Source interviews were conducted for a previous version of this article.