Business.com aims to help business owners make informed decisions to support and grow their companies. We research and recommend products and services suitable for various business types, investing thousands of hours each year in this process.
As a business, we need to generate revenue to sustain our content. We have financial relationships with some companies we cover, earning commissions when readers purchase from our partners or share information about their needs. These relationships do not dictate our advice and recommendations. Our editorial team independently evaluates and recommends products and services based on their research and expertise. Learn more about our process and partners here.
If you plan to accept credit cards online, you’ll need these services. Hub: Business Finances > Business Payments
Payment gateways and payment processors are related but distinct elements of credit card processing. You’ll likely need both services if you plan to accept credit card payments online, so understanding each is critical to making the right choice for your small business.
This guide will explain how payment gateways and payment processors fit into the credit card processing landscape.
Searching for a credit card processor and not sure where to start? Tell us a little more about your business and get customized quotes from qualified providers.
Here’s an at-a-glance look at the differences between payment gateways and payment processors:
Task/use | Payment gateway | Payment processor |
|---|---|---|
Card-present transactions | Can be entered in a virtual terminal | Card inserted into a POS system or credit card reader |
Card-not-present transactions, such as e-commerce and phone sales | E-commerce transactions processed online or entered into a virtual terminal | Can be entered into a POS system when the card’s chip or magnetic strip cannot be read properly |
Encryption of information, sending transaction data to be processed | Yes | Yes |
A payment processor is a company that handles a business’s credit card and debit card transactions and moves funds from one account to another. If you want to accept credit card and debit card payments from your customers online, over the phone or at the point of sale (POS), you must partner with a payment processor.
Payment processors can be categorized into front-end and back-end processors.

A payment gateway facilitates online payment app and card transactions in which a credit card is not physically present. The technology creates a secure connection between your business’s website and the credit card processing company to move encrypted data.
Here’s how a payment gateway works:
You can typically set up a payment gateway with your chosen credit card processing company. Some credit card processors have their own payment gateways, while others work with third-party payment gateways, such as Authorize.net, on behalf of their client businesses.
Always check a provider’s terms and conditions and understand credit card processing rules and laws before signing up. It’s best to understand how much you’ll pay upfront, monthly and per transaction.

To accept credit and debit cards online, you’ll likely need both a payment processor and a payment gateway, said Emilis Armonas, head of product at ConnectPay.
“A payment gateway is necessary to interface with customers, while a payment processor handles the behind-the-scenes movement of funds,” Armonas said. “However, in some cases, businesses may only need one or the other depending on their payment methods. For example, businesses accepting only bank transfers or PayPal may not need a traditional payment processor.”
You may be able to forego a payment gateway if you only intend to accept credit and debit card payments via an in-store point-of-sale (POS) system. However, virtual terminals accessed through your computer require a payment gateway. [Learn about the best POS systems]
According to Mastercard, small businesses that accept digital payments achieve profitable growth nearly twice as fast as businesses that do not accept digital payments.
Once you know whether your business needs a payment processor, payment gateway or both, you’ll need to research your options to choose the right provider(s) for your needs.
The best credit card processor for your business will provide the services and features you need with reasonable fees. The processors include excellent options for low- and high-volume businesses and organizations with unique needs, including high-risk credit card processing.
Frank Pagano, executive sales director at VizyPay, advised considering the following when searching for a payment processor:
Armonas added that processing speed and compatibility with major credit card companies like Visa and Mastercard are essential.
If you’re looking for a payment gateway, Armonas recommended looking for these features:
To get started on your search, check out our Clover review and our review of National Processing. Consider Android payment apps and other methods of accepting card payments on your phone if you’re specifically interested in mobile credit card processing.
[Learn how to accept payments with an iPhone]
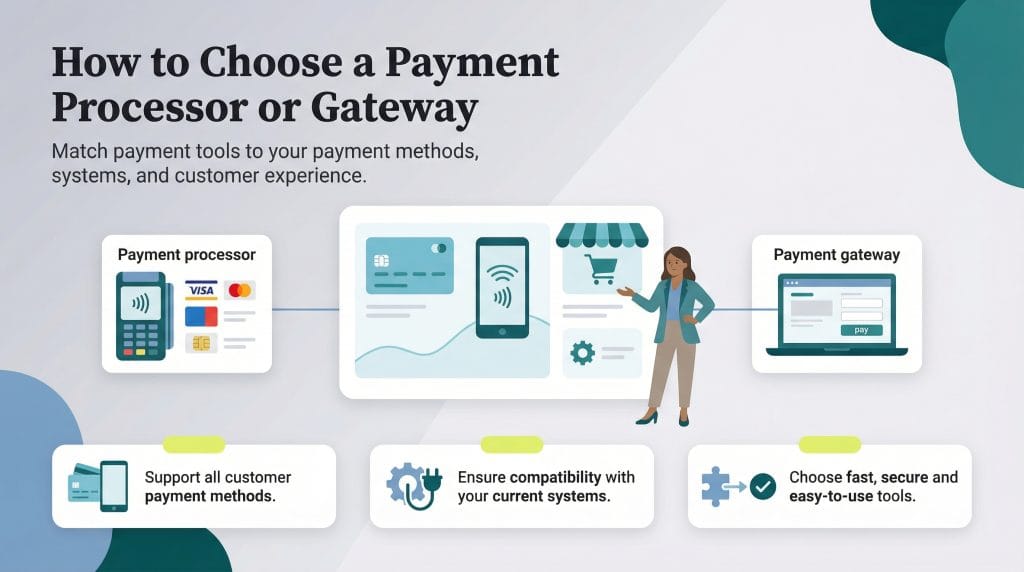
When choosing a payment processor or gateway, ensure that it supports all of your business’s needs, including a range of payment methods, compatibility with your existing systems and an easy integration process.
The difference between a merchant account and a payment gateway is that a merchant account is an arrangement with a bank that creates a space for pending transactions. Funds are held in a merchant account before being credited to your business’s bank account.
Unlike a payment gateway, a merchant account doesn’t transmit encrypted data. Instead, it transmits funds related to the transaction. The payment will be held temporarily in the merchant account as the transaction is finalized. After that, the funds will pass through the merchant account and into your business’s bank account. Read our review of Square and our Stripe review to learn how the services can act as payment facilitators.
Stripe is a payment processor that includes a payment gateway and merchant account. That enables Stripe’s merchants to accept payments online, in person, without a card present and with no additional companies or services needed.
Amazon Pay is an online payment processor that allows Amazon customers to buy from a business’s website using their Amazon accounts. To add the payment method to your site, you must set up an Amazon Pay account, configure the service and integrate it into your website.
Technically, it’s neither. PayPal is a payment aggregator, which differs from traditional payment processors in that it offers faster setup without requiring a merchant account. Aggregators use fixed pricing regardless of volume and bundle transactions under a shared account—though they are often more risk-averse and prone to account holds.
When you accept credit card payments with PayPal, they go through PayPal’s payment gateway called Payflow.